

The $720 Billion Bet: Inside SK Hynix's Race to Build Enough Memory for the AI Era
The $720 Billion Bet: Inside SK Hynix's Race to Build Enough Memory for the AI Era
MRR® Industry Intelligence Briefing Semiconductors · AI Infrastructure · Capital Markets
In August 2026, SK Group Chairman Chey Tae-won sat down with CNBC and said something no semiconductor executive says in public unless it is already happening: "prices went up too fast." His company had just committed US$720 billion to triple its memory production capacity by 2034 - described by CNBC as the largest memory fabrication buildout in history - and its market capitalization had surged past US$1 trillion, more than five times higher than a year earlier. SK Hynix had also just raised US$26.5 billion in a July 2026 Nasdaq listing, the largest amount ever raised by a foreign company on U.S. markets. None of this happened because memory chips became more interesting. It happened because the world ran out of them.
Executive Summary
The global memory market - spanning DRAM, NAND Flash, and High Bandwidth Memory (HBM) - reached US$214.80 billion in 2025 and is forecast to reach US$658.87 billion by 2031, a 20.5% CAGR, according to Navadhi Market Research's Global Memory Market Strategic Research Report 2026-2031. This figure is anchored directly to World Semiconductor Trade Statistics (WSTS), the industry's own official trade body, rather than a modeled third-party estimate - a distinction that matters, because third-party sources for this category diverge by nearly 2x for the identical 2025 base year (from US$118.9 billion to US$214.6 billion depending on methodology). WSTS's own confirmed 2026 figure of US$294.82 billion, a real +39.4% year-over-year increase, is not a forecast assumption. It already happened. Five companies - Samsung Electronics, SK hynix, Micron Technology, Kioxia Corporation, and SanDisk Corporation - control the overwhelming majority of global DRAM and NAND supply, and one company, SK hynix, has emerged as the structural centerpiece of the entire cycle: 58% of the HBM market as of Q1 2026 per Counterpoint Research, a confirmed Nvidia stable-supply agreement, and a co-development partnership feeding directly into a separate US$500 billion deal between Nvidia and SK Group.
The Research Problem: Why a Chip Shortage Is Now Showing Up in Grocery Store Prices
The standard narrative about the 2025-2026 memory market is that AI demand is driving prices up. That is true but incomplete. The more precise mechanism - and the one with the widest real-world consequences - is that AI demand is pulling wafer capacity away from the products that don't carry AI margins, and that reallocation is showing up as inflation in categories that have nothing to do with data centers.
First, the reallocation is real and quantified. Samsung, SK hynix, and Micron together produce more than 90% of the world's DRAM. When these three companies redirect fabrication capacity toward HBM - which commands substantially higher margins per wafer than commodity DRAM - the DRAM supply available for laptops, smartphones, and consumer electronics contracts by construction, not by accident. Bank of America's 2026 sector outlook forecasts DRAM revenue growth of +51% year-over-year and NAND growth of +45%, alongside ASP increases of 33% (DRAM) and 26% (NAND) - pricing power on a scale the memory industry has not exhibited in over a decade.
Second, the term "chipflation" is not a marketing phrase - it is Chairman Chey Tae-won's own description, given directly to CNBC, of the mechanism by which memory reallocation toward HBM depletes consumer electronics supply and pushes device prices upward across the broader economy. When the chairman of the company most responsible for the supply squeeze is the one naming the inflationary side effect, that is a company confirming a real market dynamic, not analysts speculating about one.
Third, the capacity response is unprecedented in scale and confirmed, not proposed. SK hynix's US$720 billion commitment to triple capacity by 2034 is real, disclosed capital allocation - not a target or an aspiration. South Korean President Lee Jae Myung separately unveiled a national plan in June 2026 to double the country's memory production within five years, including new Samsung megafabs. Two of the world's largest memory producers and their home government are simultaneously executing on the same conclusion: the current supply is not enough, and it will not be enough for years.
Three Forces Behind the Supercycle
Force 1 - HBM: The Segment Reshaping the Entire Industry
High Bandwidth Memory is the smallest memory segment by absolute dollar value and the fastest-growing by a wide margin. Yole Group's directly tracked figures show HBM growing from approximately US$35 billion in 2025 to US$60 billion in 2026 - a real +70% year-over-year increase - and to approximately US$170 billion by 2031. SK hynix was the first company to mass-produce HBM3 and HBM3E, completed development of HBM4 in September 2025 (delivering 2x the bandwidth and 40% better power efficiency than the prior generation), and TrendForce confirms HBM4 is expected to become the mainstream HBM product in the second half of 2026. Samsung is pursuing an HBM3E/HBM4 recovery to challenge SK hynix's lead; Micron is expanding aggressively via a confirmed US$7 billion HBM advanced packaging facility in Singapore.
Force 2 - Nvidia's Direct Stake in Supply Security
Nvidia does not merely purchase HBM - it now holds a confirmed stable supply agreement with SK hynix plus a co-development commitment for next-generation memory, embedded within a separate US$500 billion deal between Nvidia and SK Group that includes new data centers built jointly with SK Telecom by 2027. When the world's most valuable AI chip company signs a direct co-development and supply-security arrangement with a memory supplier rather than relying on the open market, that is the clearest available signal that memory availability - not GPU availability - is the binding constraint AI infrastructure buildout is now managing around.
Force 3 - A Capital Response Measured in the Hundreds of Billions
SK hynix's US$720 billion capacity commitment and South Korea's national doubling plan are not isolated corporate decisions - they are a coordinated, multi-year industrial response to a demand signal that both the company and its home government have concluded is structural rather than cyclical. Capacity investment on this scale takes years to convert into shipped output; the current supply-demand imbalance is not resolving in the next several quarters regardless of near-term price movements.
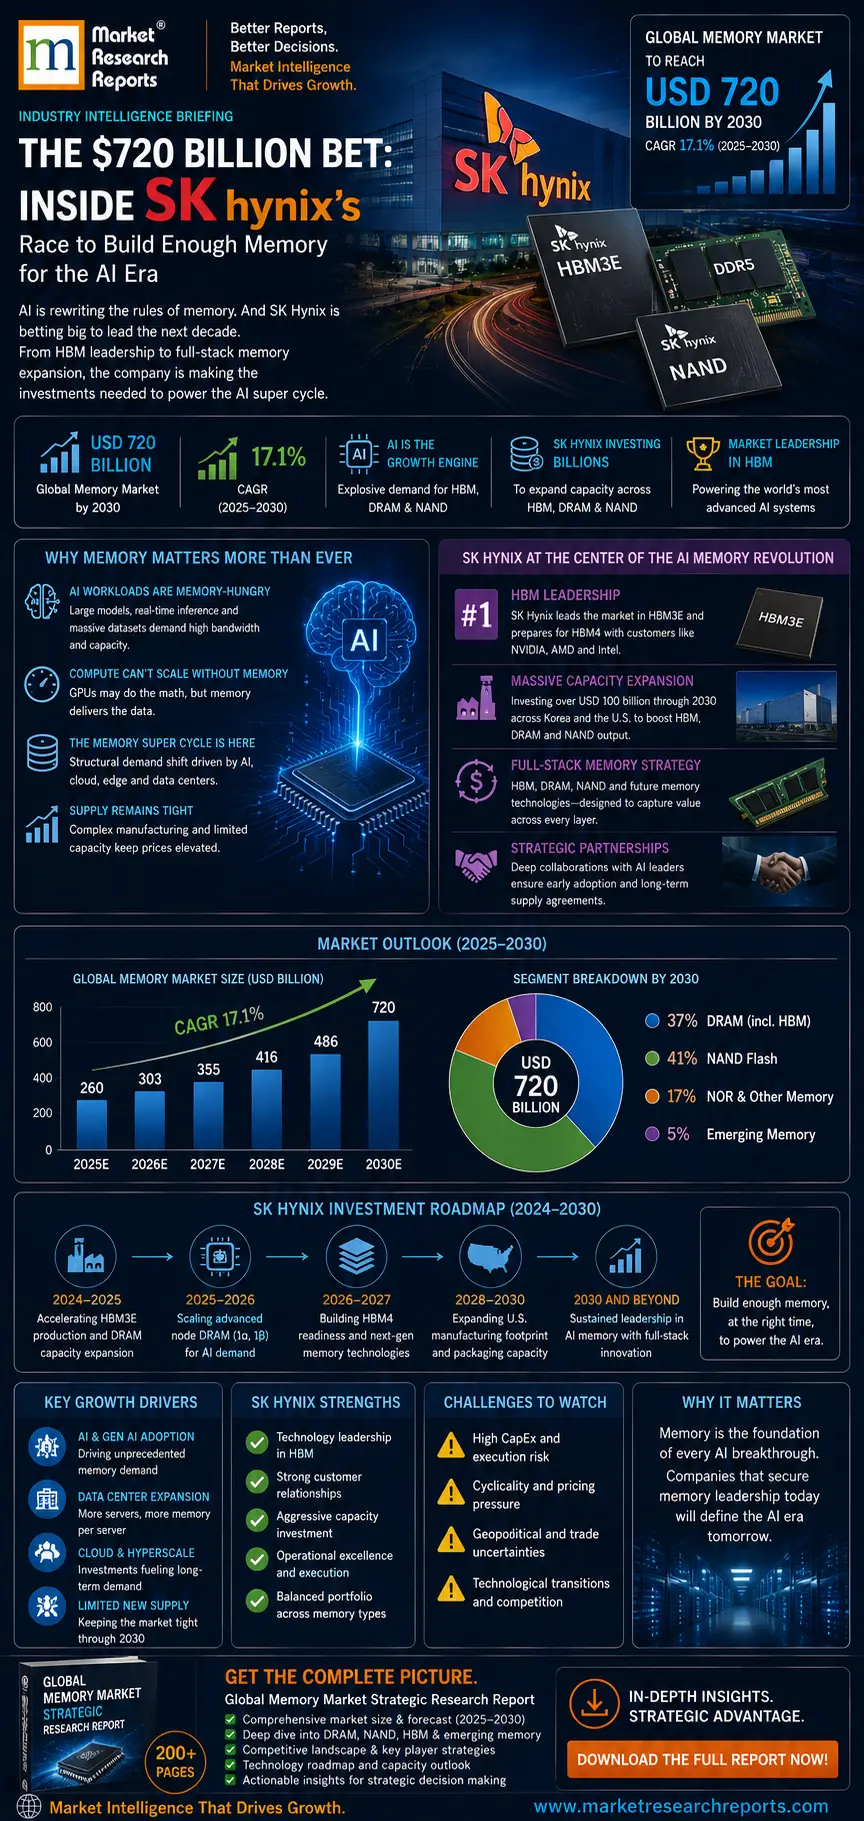
The Competitive Landscape: Who Controls the Supply
| Company | Segment Position | Confirmed 2025-2026 Metrics | Structural Position |
|---|---|---|---|
| SK hynix Inc. | HBM market leader; #2 DRAM supplier | 58% HBM share (Counterpoint, Q1 2026) / 56.4% (IDC/SEC filing); US$1T+ market cap; US$720B capacity commitment; US$26.5B Nasdaq listing (largest ever by a foreign company) | Confirmed Nvidia stable-supply agreement plus co-development partnership; described by Bank of America as the memory industry's "Top Pick" |
| Samsung Electronics | Overall market leader (~28-33% share); DRAM leader | 21% HBM share (Counterpoint, Q1 2026) | Pursuing HBM3E/HBM4 recovery to challenge SK hynix's lead while defending broad DRAM/NAND leadership |
| Micron Technology | Balanced DRAM/NAND/HBM portfolio | 21% HBM share (Counterpoint, Q1 2026); US$7B Singapore HBM packaging facility (confirmed, groundbreaking Jan 2025) | Aggressive HBM capacity expansion targeting AI data center demand directly |
| Kioxia Corporation | NAND-focused specialist | Among 5 companies holding 95%+ combined NAND market share (SK hynix SEC filing, citing IDC) | Cross-verified NAND position consistent with the companion SSD Market report |
| SanDisk Corporation | NAND-focused specialist, independent since 2025 | Among 5 companies holding 95%+ combined NAND market share | Independent since its 2025 spin-off from Western Digital |
Source: Navadhi Market Research, Global Memory Market Strategic Research Report 2026-2031; SK hynix SEC-filed prospectus (Form 424B4/F-1A, citing IDC); Counterpoint Research via CNBC (Katie Tarasov), August 13, 2026.
Analyst Insight
The most consequential detail in this market is not the growth rate - it is who is confirming the growth rate. WSTS's +39.4% 2026 figure is not a projection; it is a disclosed, already-realized number from the industry's own trade statistics body. SK hynix's US$720 billion commitment is not guidance; it is capital already being allocated. Nvidia's supply agreement with SK hynix is not a rumor; it is a confirmed structural arrangement sitting inside a US$500 billion bilateral deal. When the demand signal, the capacity response, and the customer lock-in are all independently confirmed rather than modeled, the case for a multi-year (not multi-quarter) supercycle is considerably stronger than the typical semiconductor upcycle narrative - which is precisely why this report models a 20.5% CAGR that deliberately moderates the real, confirmed 39.4% 2026 spike rather than extrapolating it, while still reflecting genuine structural demand.
Strategic Lessons for Market Participants
| Observation | Strategic Implication |
|---|---|
| SK hynix's HBM share is contested from two directions (Samsung recovery, Micron expansion) | Investors and buyers tracking HBM supply concentration should monitor quarterly share shifts closely - the current ~58% leadership position is real but not structurally guaranteed through 2031 |
| "Chipflation" signals memory reallocation effects extending beyond the semiconductor sector | Companies in consumer electronics, automotive, and industrial equipment relying on commodity DRAM/NAND should factor sustained input cost inflation into 2026-2027 planning, not treat current pricing as transitory |
| Capacity investment cycles (SK hynix's $720B, South Korea's national plan) take years to convert to shipped supply | The current supply-demand imbalance is a multi-year structural condition, not a near-term pricing anomaly correcting within 2-3 quarters |
| Nvidia's direct supply agreement with SK hynix reflects a broader trend toward vertical supply security | Companies dependent on HBM-adjacent components should evaluate direct supplier relationships rather than assuming open-market availability, mirroring the strategy AI chip leaders have already adopted |
Frequently Asked Questions
Why does WSTS's figure differ from other market research estimates?
WSTS (World Semiconductor Trade Statistics) is the semiconductor industry's own official, non-profit trade association - its figures reflect direct industry shipment data rather than modeled third-party estimation. This report anchors to WSTS specifically because third-party sources for the memory market diverge by nearly 2x for the identical 2025 base year (from US$118.9 billion to US$214.6 billion), and WSTS represents the highest-confidence primary source available.
Is the HBM share discrepancy between sources (56.4% vs. 58%) a data error?
No - both figures are real and independently sourced. The 56.4% figure comes from SK hynix's own SEC-filed prospectus, citing IDC data. The 58% figure comes from Counterpoint Research, cited directly by CNBC in its August 2026 reporting. Both are credible research firms using different methodologies; this report presents both rather than silently reconciling them to a single number.
What is driving the HBM4 timeline specifically?
SK hynix completed HBM4 development in September 2025, delivering 2x the bandwidth and 40% better power efficiency than HBM3E via 2,048 I/O and operation speeds above 10 Gbps. TrendForce confirms HBM4 is expected to become the mainstream HBM product in the second half of 2026, with Samsung and Micron both pursuing competitive HBM4 roadmaps to contest SK hynix's early lead.
How does the memory market relate to the SSD and data center infrastructure markets?
Directly. This report covers the chip-level DRAM, NAND, and HBM market - distinct from Navadhi's companion Global SSD Market report, which covers finished storage devices built using NAND flash, and its Global Data Center Wire and Cable report, which covers the physical infrastructure connecting the servers these chips power. All three markets are experiencing the same AI-driven demand cycle from different points in the same supply chain, and the five-company memory structure identified here is directly cross-verified against the companion SSD report's own NAND-specific company findings.
Is "chipflation" likely to affect consumer electronics prices through 2027?
Based on the confirmed reallocation dynamics - DRAM and NAND capacity shifting toward higher-margin HBM production at the three companies controlling 90%+ of global DRAM supply - sustained upward pressure on consumer device pricing is a reasonable structural expectation through the current capacity investment cycle, though the magnitude will depend on how quickly new capacity (including SK hynix's $720B commitment) converts to shipped commodity-grade supply.
For full market sizing, regional forecasts, and vendor profiles across the global memory landscape, see our Global Memory Market Strategic Research Report 2026-2031. For the finished storage devices built from this same NAND supply chain, read our companion report on the Global Solid State Drive (SSD) Market. For bespoke semiconductor market analysis, commission custom research.