

The Price of Resilience: What Supply Chain Restructuring Is Actually Costing the Companies Doing It - and Who Is Profiting
The Price of Resilience: What Supply Chain Restructuring Is Actually Costing the Companies Doing It - and Who Is Profiting
MRR® Industry Intelligence Briefing Supply Chain · Reshoring · Industrial Policy
When the US CHIPS and Science Act authorized USD 52.7 billion in federal funding for domestic semiconductor manufacturing, it created the most visible price tag ever attached to a supply chain resilience decision. TSMC's Arizona facility alone received USD 6.6 billion in direct grants plus loan guarantees against a total committed construction investment exceeding USD 40 billion — the capital cost of moving a single manufacturer's advanced packaging capacity from Taiwan to Phoenix. Multiplied across the electronics, pharmaceutical, automotive, and defense sectors simultaneously attempting the same relocation and redundancy investments, the result is a USD 185 billion market for supply chain resilience advisory, technology, logistics, and manufacturing relocation services in 2025, growing at 8.25% annually toward USD 297.4 billion by 2031. This briefing examines where that spending is actually going, which companies are capturing the largest share of it, and why the cost of resilience is proving to be considerably higher than the pre-pandemic supply chain models that first calculated it.
Executive Summary
The global Supply Chain Resilience (SCR) and Nearshoring Investment Market is valued at USD 185.0 billion in 2025, anchored by the disclosed revenues of the ten leading companies that dominate the sector, expanding at an 8.25% CAGR toward USD 297.4 billion by 2031 — a cumulative absolute growth of 60.8% over the six-year forecast period, according to Market Research Reports® Inc. The market encompasses five solution segments: supply chain consulting and strategy, supply chain technology and digital solutions, nearshoring and manufacturing relocation services, logistics and freight resilience management, and supply chain risk management and insurance. It is structured around seven application verticals, of which electronics and semiconductor manufacturing is simultaneously the largest (USD 42.6 billion in 2025) and the fastest-growing (9.2% CAGR to USD 72.3 billion by 2031), catalyzed by multi-billion-dollar fab constructions in the United States, Germany, and Japan. North America is the dominant geography, holding a 38.0% market share valued at USD 70.3 billion in 2025, with the United States alone commanding USD 59.1 billion, driven by the CHIPS Act, the Inflation Reduction Act, and USMCA-anchored nearshoring in Mexico. The market's growth trajectory reflects a structural and policy-driven investment cycle rather than a cyclical demand upturn — the capital commitments underlying it are multi-year, contractually binding, and largely irreversible on any horizon relevant to the current forecast period. The constraint on faster growth is not the absence of capital or political will; it is the execution capacity of the advisory, logistics, and real estate ecosystem that must accommodate simultaneous large-scale relocation activity across multiple sectors and geographies.
The Research Problem: What "Resilience" Has Actually Cost
The pre-pandemic supply chain optimization paradigm was built on a well-established principle: concentrated, single-source, geographically distant supply chains reduce cost, and those cost savings compound annually across the period during which they are undisturbed. The 2020-2022 disruption period quantified the cost of that concentration, but the precise magnitude of the alternative — what resilient supply chains cost relative to optimized supply chains — is still being calculated in real time as the CHIPS Act-era construction projects complete their first phases.
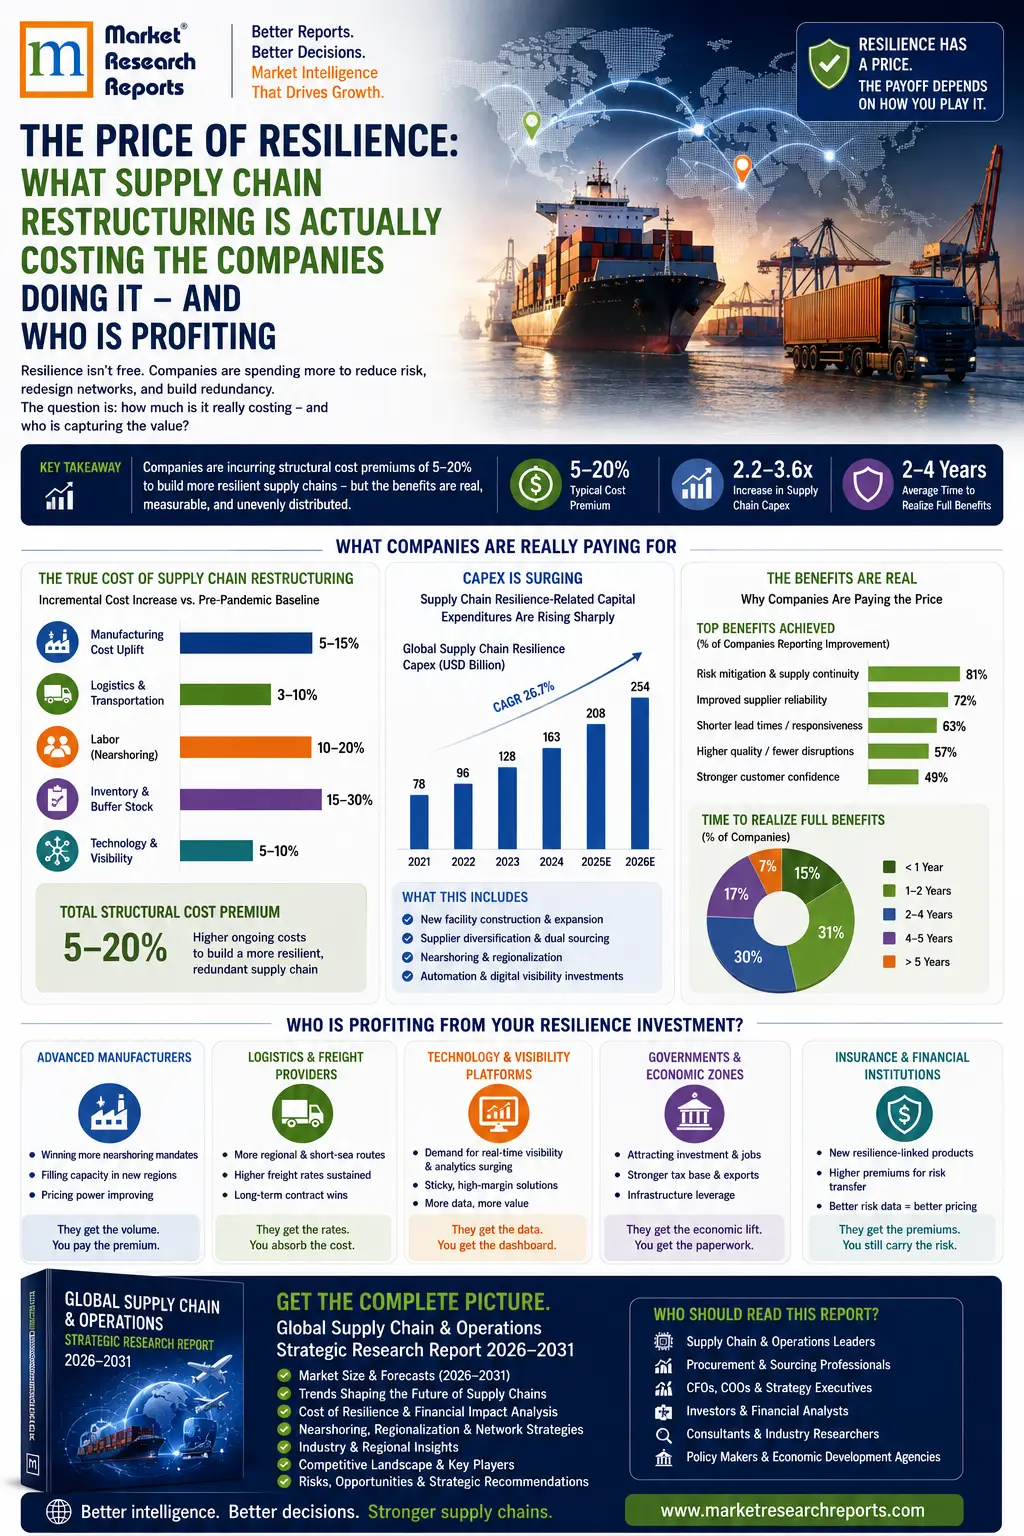
The TSMC Arizona case is the most granular publicly disclosed example available. The USD 40+ billion total investment in the Arizona facility — of which USD 6.6 billion in direct federal grants plus USD 5.0 billion in federal loans mitigates a portion of the capital cost — will produce leading-edge semiconductor wafers at a manufacturing cost structurally higher than the equivalent production in Taiwan, reflecting higher US labor costs, higher construction costs, and the absence of the dense supplier ecosystem that surrounds TSMC's home base in Hsinchu. TSMC's own public communications and analyst commentary have consistently indicated that Arizona wafers will carry a cost premium of 30-50% relative to Taiwan-equivalent production, at least in the facility's early operational years before the cost curve normalizes with volume and supplier ecosystem development.
This cost differential — resilience premium over optimization — is what the USD 185 billion SCR market is ultimately servicing. Consulting firms are being paid to design supply chain structures that accept a measurable efficiency cost in exchange for reduced concentration risk. Technology platforms are being sold on the premise that digital visibility and scenario planning capability can partially substitute for physical redundancy. Industrial real estate investment trusts are benefiting from the demand for warehouse and logistics capacity adjacent to the newly nearshored manufacturing facilities. The market is real and growing, but its growth is fundamentally funded by the premium that corporations and governments have collectively decided to pay for supply chain outcomes that are less efficient and more resilient than the ones they previously ran.
Three Structural Forces Driving the Market
Force 1 — US Industrial Policy: CHIPS Act, IRA, and the Policy-Anchored Investment Supercycle
The CHIPS and Science Act (August 2022) authorized USD 52.7 billion across direct grants, loan programs, and research investment for domestic semiconductor manufacturing. The Inflation Reduction Act (August 2022) introduced USD 369 billion in clean energy and manufacturing incentives, explicitly tied to domestic content requirements for electric vehicles, solar panels, batteries, and wind energy components. Together, these two pieces of legislation represent the largest explicit industrial policy investment in the United States since the post-World War II era and have created a demand pull for supply chain restructuring services that is policy-mandated rather than purely market-driven. When domestic content requirements are embedded in subsidy eligibility criteria — as both the CHIPS Act and IRA do — corporations that want access to the subsidies must physically restructure their supply chains, creating non-discretionary demand for the relocation, real estate, and logistics services that execute that restructuring.
Force 2 — Mexico Nearshoring: The Largest Single Geography Beneficiary
Mexico received FDI at near-record levels from 2022 through 2025, driven substantially by USMCA-compliant manufacturing relocations from Asia. The USMCA's regional value content requirements for automotive components — requiring 75% North American regional value content to qualify for preferential tariff treatment — created the most explicit policy-mandated nearshoring incentive outside the semiconductor sector. The beneficiaries are concentrated: the US-Mexico border corridor states (Nuevo León, Coahuila, Chihuahua, and Baja California), industrial real estate operators with Mexican footprints (Prologis, VESTA, Fibra Plus), and the logistics and customs brokerage firms managing the cross-border flow of goods produced under the new regional supply structures. Prologis — the world's largest logistics REIT and one of the ten anchor companies profiled in the research — has disclosed accelerating demand for industrial real estate across its Mexican portfolio, with occupancy rates and rental rates in border corridor markets outperforming the company's global portfolio.
Force 3 — Technology Platform Adoption: Digital Supply Chain Investment as a Resilience Proxy
Supply Chain Technology & Digital Solutions — the second-largest segment at USD 35.4 billion in 2025, growing at 9.8% CAGR — represents the component of the market where physical restructuring is being supplemented by digital visibility investment. Kinaxis, one of the ten profiled companies, provides supply chain orchestration software that enables concurrent planning across supply networks; its disclosed revenue and customer growth reflect accelerating enterprise investment in digital twin and scenario planning capability as a partial complement to (not substitute for) physical network diversification. SAP's supply chain modules embedded in its broader ERP platform similarly show elevated adoption as enterprises seek visibility across newly complex dual-source supply networks that require more active management than the simplified single-source structures they replaced.
Competitive Landscape: The Three-Tier Market Structure
| Company | Primary SCR Revenue Category | Scale Indicator | Structural Position |
|---|---|---|---|
| DHL Group (Deutsche Post DHL) | Logistics & Freight Resilience Management | EUR 94.4B group revenue (2024); Supply Chain division a major contributor | Largest logistics footprint globally; benefits directly from cross-border nearshoring trade flows created by CHIPS Act and IRA investments |
| A.P. Moller-Maersk | Freight resilience, integrated logistics | Revenue normalizing from pandemic peaks; USD 46.3B (2023) | Ocean freight plus integrated land logistics; direct beneficiary of nearshoring trade route development |
| Accenture PLC | Supply chain consulting & strategy, technology implementation | Total FY2024 revenue USD 64.9B; Supply Chain practice a disclosed multi-billion segment | Consulting and SI execution role — captures advisory fees as corporations design resilience strategies, then implementation fees as they execute them |
| Prologis Inc. | Industrial real estate for nearshoring manufacturing | USD 8.0B revenue (2024); Mexican portfolio outperforming global average | Indirect but direct beneficiary — nearshoring creates demand for warehouse/distribution real estate adjacent to new manufacturing facilities |
| C.H. Robinson Worldwide | Freight brokerage and logistics orchestration | USD 16.8B gross revenue (2024) | Cross-border freight management for USMCA-compliant supply chains |
| Kuehne+Nagel International | Sea/air freight, contract logistics | CHF 26.5B revenue (2024) | Diversified logistics with expanding Latin America footprint aligned with Mexico nearshoring |
| SAP SE | Supply chain technology & digital solutions | EUR 34.2B total revenue (2024); ERP supply chain modules core product line | Embedded supply chain software position creates switching cost and recurring revenue from SCR-related ERP upgrades |
| Kinaxis Inc. | Supply chain orchestration software | CAD 470M+ revenue (2025); accelerating enterprise bookings | Pure-play SCR technology; most directly exposed to the supply chain planning software market |
Sources: Disclosed company annual reports and earnings releases 2023-2025. Market sizing from Market Research Reports® Inc., Global Supply Chain Resilience & Nearshoring Investment Market Strategic Research Report 2026-2031.
Regional Breakdown: Where the Capital Is Being Deployed
| Region | 2025 Value | 2031 Forecast | Key Driver |
|---|---|---|---|
| North America | USD 70.3B (38% share) | USD 108.0B | CHIPS Act ($52.7B), IRA ($369B incentives), USMCA nearshoring; US alone $59.1B |
| Europe | Major contributor | Solid growth | EU Critical Raw Materials Act, CBAM carbon border adjustment, automotive supply chain EV transition |
| Asia-Pacific | Significant share | Steady growth | China+1 supplier diversification strategies; India semiconductor manufacturing buildout |
| Latin America | Growing rapidly | Elevated CAGR | Mexico nearshoring wave; Brazil industrial policy; Colombia and Chile logistics infrastructure |
| Middle East & Africa | Smaller base | Emerging | GCC regional supply chain diversification; Saudi Vision 2030 industrial diversification |
Source: Market Research Reports® Inc., Global Supply Chain Resilience & Nearshoring Investment Market Strategic Research Report 2026-2031.
Analyst Insight
The USD 185 billion SCR market figure is large but it understates the total capital flowing through supply chain restructuring in 2025, because it captures the B2B service and technology market rather than the total capital expenditure. When TSMC commits USD 40 billion to the Arizona fab, the USD 40 billion itself flows into construction, equipment, and land — none of which is captured in the SCR market size. What the USD 185 billion captures is the advisory, logistics, technology, and relocation services layer that facilitates the structural change: the consulting fees, the industrial real estate leases, the freight brokerage commissions, the ERP upgrade contracts, and the risk management and insurance premiums that are increasing in line with supply network complexity. The consultancy and logistics firms profiled here are the intermediary layer capturing a service fee on a capital restructuring program of considerably larger scale. This distinction matters for market sizing context: the SCR market is large, but it is the invoice for a restructuring program whose underlying capital budget is an order of magnitude larger.
Strategic Lessons for Market Participants
| Observation | Strategic Implication |
|---|---|
| North America commands 38% of the market and the US commands $59.1B — the highest single-country concentration in the dataset | Vendors without established US and Mexico presence face a structural growth ceiling; the policy-anchored nature of CHIPS Act and IRA spending means procurement is concentrated among relationship-qualified vendors with demonstrated domestic US capability |
| Electronics & semiconductor manufacturing is both the largest and fastest-growing application segment | SCR vendors that have not developed semiconductor sector expertise and client relationships are likely to underperform market growth rates, since the sector that is growing fastest also has the most complex and specialized supply chain restructuring requirements |
| The nearshoring wave is compounding industrial real estate demand independently of overall economic conditions | Prologis and industrial REIT peers with Mexican and US Sunbelt exposure are structurally positioned to benefit from USMCA-driven nearshoring regardless of broader real estate market conditions, since the demand driver (policy-mandated near-source manufacturing) does not respond to interest rates the way speculative real estate demand does |
| Technology platforms with embedded switching cost are the highest-margin SCR participation mode | SAP's ERP position and Kinaxis's orchestration software generate recurring revenue and high switching cost that pure advisory or logistics participation cannot match; technology-led SCR participation is structurally more defensible than services-only positioning |
Frequently Asked Questions
Is the CHIPS Act and IRA nearshoring wave a structural or cyclical trend?
Structural. The CHIPS Act's funding is committed over five-plus years through the CHIPS Program Office, and the IRA's domestic content provisions are embedded in tax credit eligibility — both require physical supply chain restructuring as a condition of access to the incentive, not as a discretionary choice. The spending that flows from them is legally conditioned on domestic or near-shore sourcing, making it durable regardless of the broader economic cycle.
Why is Mexico rather than the US itself capturing the largest nearshoring manufacturing investment?
Mexico's USMCA-qualifying status, significantly lower manufacturing labor costs, and established proximity to the US market make it the optimal location for labor-intensive manufacturing that must meet North American regional content requirements but cannot economically do so using US labor costs. The electronics assembly, automotive components, and consumer goods assembly sectors are the primary beneficiaries. High-tech, capital-intensive manufacturing (advanced semiconductor fabs, EV battery plants) tends to locate in the US itself to access CHIPS Act and IRA direct subsidies, while more labor-intensive assembly moves to Mexico.
Which segment within the SCR market is most directly exposed to a US-China trade environment deterioration?
Nearshoring & Manufacturing Relocation Services, which at USD 21.8 billion in 2025 is growing at 10.2% CAGR — the fastest of the five segments — and is most directly driven by China+1 supplier diversification decisions that accelerate with each escalation in US-China trade policy. A further tariff escalation or technology export control tightening would increase the pace of relocation from China to alternative sourcing geographies, directly benefiting this segment.
Is the resilience premium — the higher cost of diversified supply chains versus optimized ones — sustainable?
Where the resilience premium is policy-mandated (CHIPS Act, IRA, USMCA), it is sustainable for the duration of the relevant policy. Where it is purely corporate risk management — a voluntary decision to accept higher supply chain costs in exchange for lower concentration risk — it is more vulnerable to cost pressure during economic downturns. The 8.25% CAGR reflects an overall moderate growth rate precisely because the market includes both the policy-mandated segment (growing faster) and the voluntary corporate resilience segment (more cyclically sensitive).
For full segment, application, regional, and country-level detail, complete methodology, and all ten company profiles, see our Global Supply Chain Resilience & Nearshoring Investment Market Strategic Research Report. For bespoke supply chain analysis, commission custom research.