Global B2B Wholesale Travel Distribution Market Strategic Research Report

By Type: GDS-Based Wholesale Distribution, API-Driven Direct Connect Platforms, NextGen NDC Protocol Distribution, Bedbank and Hotel Wholesale Aggregation, Ground Transport and Transfers Wholesale
By Application: Online Travel Agencies (OTAs) and Meta-Search Platforms, Tour Operators and Package Travel Wholesalers, Corporate Travel Management Companies (TMCs), Retail Travel Agents and Consortia Networks, Airline and Hotel Direct Retailing Programs
Regional Forecast: Asia Pacific, Latin America, MEA, Europe, North America
Key Players: Amadeus IT Group, Sabre Corporation, Travelport, HBX Group (Hotelbeds), Web Travel Group (WebBeds), Expedia Group (B2B Segment), TBO Holidays, Booking Holdings B2B, Duffel Technologies, Verteil Technologies
Übersicht
The global B2B wholesale travel distribution market is being remade from the inside out — and the incumbents building today's roadmaps around GDS economics are optimizing for a shrinking pie.
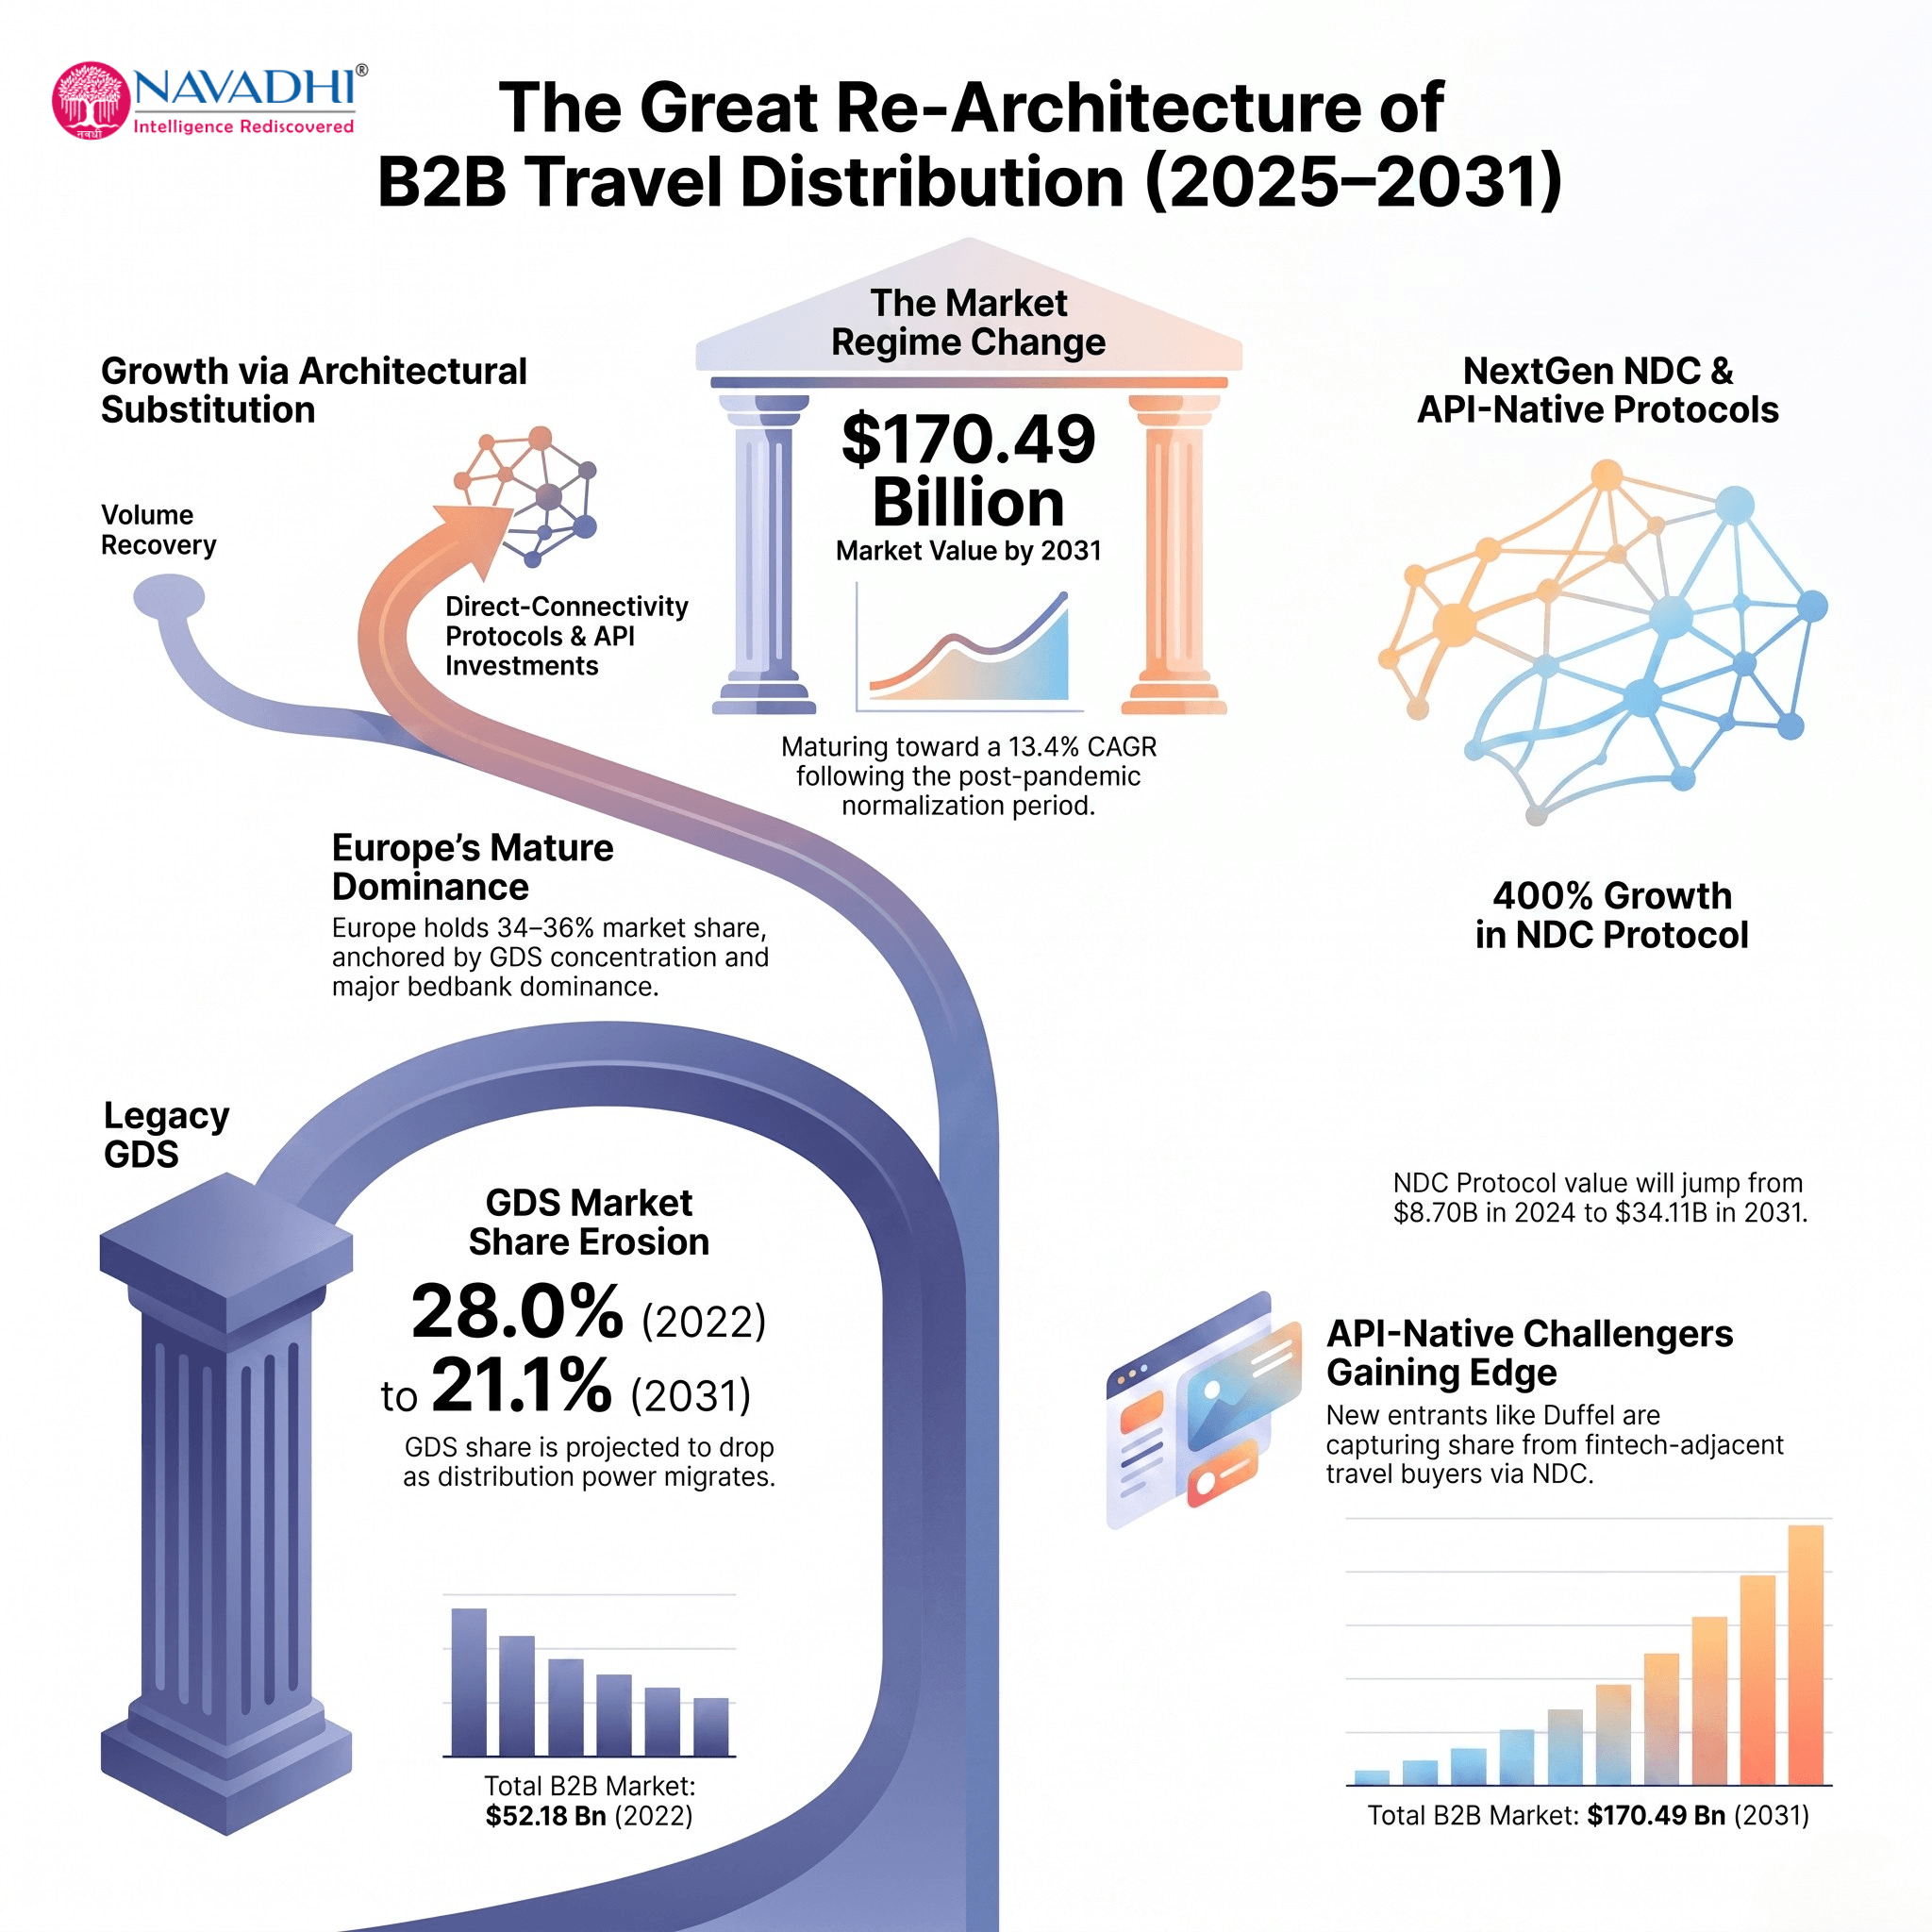
The market reached an estimated USD 80.35 Bn in 2025, up from USD 52.18 Bn in 2022 — a 15.5% CAGR driven by the tailwind of post-pandemic demand normalization. That tailwind is now fading. Our forecast puts the market at USD 170.49 Bn by 2031, a 13.4% CAGR through the period — still robust, but the 210-bps deceleration is not noise. It marks a regime change: growth is shifting from volume recovery to architectural substitution.
The core dynamic: distribution power is migrating from intermediated fare buckets to direct, protocol-native connectivity.
NDC is the structural disruptor, not a niche segment. The NextGen NDC Protocol pool is projected to grow 4x, from USD 8.70 Bn (2024) to USD 34.11 Bn (2031) — and in doing so, will compress GDS's share of the total market from 28.0% (2022) to 21.1% (2031). This is not gradual erosion; it is a compounding annual share transfer of roughly 100 bps, and it accelerates as airline and hotelier API investment reaches critical mass.
The winners will be platforms that arbitrage the transition, not resist it. Bedbank and hotel wholesale consolidators are already positioning to capture margin from fragmented regional inventory — a hedge against GDS disintermediation rather than a bet against it.
Base-effect normalization explains the headline deceleration, but masks a bifurcated reality underneath: legacy GDS channels face margin compression, while API-driven and NDC channels are compounding volume gains that will outpace the blended market average for the balance of the decade.
Europe's market share was 34–36% in 2025, anchored by GDS infrastructure concentration, Hotelbeds' Mallorca-based bedbank dominance, and a mature OTA ecosystem. This is a defensible but low-growth incumbency position.
The strategic imperative for 2025–2026: Every participant in this value chain — GDS operators, bedbanks, airlines, hoteliers, and OTAs — is now being forced to choose a side of the distribution architecture divide. Those who delay that choice risk optimizing legacy infrastructure for a shrinking share of a growing market.
Market snapshot
Global B2B Wholesale Travel Distribution Market Strategic Research Report snapshot, 2025–2031
 © MarketResearchReports.comDisclaimer: The actual data may vary in the final report which undergoes verification check post order confirmation.
Segments covered in this report
Table of contents
01Executive Summary
- 1.1 Market Synopsis
- 1.2 Key Findings
- 1.3 Strategic Recommendations
02Industry Overview & Forecast
- 2.1 Market Definition & Scope
- 2.2 Market Value Forecast, 2025-2032 (Value)
- 2.3 CAGR Analysis & Confidence Intervals
- 2.4 Historical Market Review, 2019-2024
- 2.5 Scenario Analysis (Base, Bull, Bear Cases)
03Market Segmentation by Type
- 3.1 Market by Type Overview
- 3.2 GDS-Based Wholesale Distribution (Value)
- 3.3 API-Driven Direct Connect Platforms (Value)
- 3.4 NextGen NDC Protocol Distribution (Value)
- 3.5 Bedbank & Hotel Wholesale Aggregation (Value)
- 3.6 Ground Transport & Transfers Wholesale (Value)
04Market Segmentation by Application
- 4.1 Market by Application Overview
- 4.2 Online Travel Agencies (OTAs) & Meta-Search Platforms (Value)
- 4.3 Tour Operators & Package Travel Wholesalers (Value)
- 4.4 Corporate Travel Management Companies (TMCs) (Value)
- 4.5 Retail Travel Agents & Consortia Networks (Value)
- 4.6 Airline & Hotel Direct Retailing Programs (Value)
05Regional Market Forecast
- 5.1 Regional Revenue Share & CAGR (2024 vs 2032)
- 5.2 Asia Pacific (Value)
- 5.3 North America (Value)
- 5.4 Europe (Value)
- 5.5 Middle East & Africa
- 5.6 Latin America
06Country-Level Market Forecast
- 6.1 Top Countries Overview
- 6.2 United States
- 6.3 United Kingdom
- 6.4 Germany
- 6.5 China
- 6.6 India
- 6.7 United Arab Emirates
07Growth Drivers & Inhibitors
- 7.1 NextGen NDC Protocol Adoption Accelerating Airline Direct Content Distribution
- 7.2 Bedbank Consolidation Driving Scale Economics and Inventory Depth
- 7.3 API-First Connectivity Replacing Legacy GDS Screen-Scraping Infrastructure
- 7.4 Market Restraints & Challenges
- 7.5 Opportunities & White-Space Analysis
08Key Company Profiles
- 8.1 Amadeus IT Group — Revenue, Strategy, Key Products
- 8.2 Sabre Corporation — Revenue, Strategy, Key Products
- 8.3 Travelport Worldwide — Revenue, Strategy, Key Products
- 8.4 Hotelbeds Group — Revenue, Strategy, Key Products
- 8.5 WebBeds (Webbeds by Jumeirah Group) — Revenue, Strategy, Key Products
- 8.6 TBO Holidays (TBO.com) — Revenue, Strategy, Key Products
- 8.7 Expedia Group B2B (Expedia TAAP & Partner Solutions) — Revenue, Strategy, Key Products
- 8.8 Booking Holdings (Booking.com for Business & Agoda B2B) — Revenue, Strategy, Key Products
- 8.9 Duffel Technologies — Revenue, Strategy, Key Products
- 8.10 Air France-KLM / IATA NDC Working Group Participants (AeroCRS / Verteil Technologies) — Revenue, Strategy, Key Products
09Competitive Landscape
- 9.1 Market Concentration & Competitive Intensity
- 9.2 Market Share Analysis (2024)
- 9.3 Competitive Positioning Matrix
- 9.4 Recent Developments: M&A, Partnerships & Product Launches (2023-2025)
10Porter's Five Forces Analysis
- 10.1 Threat of New Entrants
- 10.2 Bargaining Power of Buyers
- 10.3 Bargaining Power of Suppliers
- 10.4 Threat of Substitute Products
- 10.5 Competitive Rivalry Intensity
11PESTLE Analysis
- 11.1 Political Factors
- 11.2 Economic Factors
- 11.3 Social & Demographic Factors
- 11.4 Technological Factors
- 11.5 Legal & Regulatory Factors
- 11.6 Environmental Factors
12SWOT Analysis
- 12.1 Market-Level Strengths
- 12.2 Market-Level Weaknesses
- 12.3 Strategic Opportunities
- 12.4 External Threats
13Future Trends & Outlook
- 13.1 AI-Powered Dynamic Pricing Engines Embedded in Wholesale API Middleware
- 13.2 Offer & Order Management Replacing PNR-Based GDS Booking Architecture
- 13.3 Branded Fare Merchandising and Ancillary Bundling via NDC Storefronts
- 13.4 Long-Term Market Outlook (2033-2035)
- 13.5 Investment & M&A Activity Outlook
Tables and figures
Exhibit 2.1: Forecast of Global Market YoY Growth Rate & CAGR Summary (in %)
Exhibit 2.2: Forecast of Global (in USD Bn)
Exhibit 2.3: Forecast of North America (in USD Bn)
Exhibit 2.4: Forecast of Europe (in USD Bn)
Exhibit 2.5: Forecast of Asia Pacific (in USD Bn)
Exhibit 2.6: Forecast of Latin America (in USD Bn)
Exhibit 2.7: Forecast of MEA (in USD Bn)
Exhibit 3.8: Forecast of GDS-Based Wholesale Distribution (in USD Bn)
Exhibit 3.9: Forecast of Amadeus GDS Wholesale (in USD Bn)
Exhibit 3.10: Forecast of Sabre GDS Wholesale (in USD Bn)
Exhibit 3.11: Forecast of Travelport GDS Wholesale (in USD Bn)
Exhibit 3.12: Forecast of Other GDS Participants (in USD Bn)
Exhibit 3.13: Forecast of API-Driven Direct Connect Platforms (in USD Bn)
Exhibit 3.14: Forecast of REST/JSON API Connectivity Hubs (in USD Bn)
Exhibit 3.15: Forecast of White-Label API Reseller Platforms (in USD Bn)
Exhibit 3.16: Forecast of Aggregator-to-Aggregator API Exchanges (in USD Bn)
Exhibit 3.17: Forecast of NextGen NDC Protocol Distribution (in USD Bn)
Exhibit 3.18: Forecast of Airline NDC Level 4 Certified Channels (in USD Bn)
Exhibit 3.19: Forecast of NDC Aggregator Middleware Providers (in USD Bn)
Exhibit 3.20: Forecast of NDC-Enabled OTA & TMC Connections (in USD Bn)
Exhibit 3.21: Forecast of Bedbank & Hotel Wholesale Aggregation (in USD Bn)
Exhibit 3.22: Forecast of Global Bedbank Platforms (in USD Bn)
Exhibit 3.23: Forecast of Regional Hotel Wholesale Aggregators (in USD Bn)
Exhibit 3.24: Forecast of Vacation Rental & Alternative Accommodation Wholesale (in USD Bn)
Exhibit 3.25: Forecast of Ground Transport & Transfers Wholesale (in USD Bn)
Exhibit 3.26: Forecast of Airport Transfer & Shuttle Wholesale (in USD Bn)
Exhibit 3.27: Forecast of Car Rental B2B Wholesale (in USD Bn)
Exhibit 3.28: Forecast of Rail & Coach Wholesale Distribution (in USD Bn)
Exhibit 4.29: Forecast of Online Travel Agencies (OTAs) & Meta-Search Platforms (in USD Bn)
Exhibit 4.30: Forecast of Full-Service OTA B2B Portals (in USD Bn)
Exhibit 4.31: Forecast of Meta-Search B2B Feed Aggregation (in USD Bn)
Exhibit 4.32: Forecast of Niche & Vertical OTA Platforms (in USD Bn)
Exhibit 4.33: Forecast of Retail Travel Agents & Consortia Networks (in USD Bn)
Exhibit 4.34: Forecast of Independent Travel Agencies (in USD Bn)
Exhibit 4.35: Forecast of Consortia & Cooperative Networks (in USD Bn)
Exhibit 4.36: Forecast of Franchise Travel Agency Groups (in USD Bn)
Exhibit 4.37: Forecast of Airline & Hotel Direct Retailing Programs (in USD Bn)
Exhibit 4.38: Forecast of Airline B2B Direct Offer Distribution (in USD Bn)
Exhibit 4.39: Forecast of Hotel Chain Direct B2B Rate Programs (in USD Bn)
Exhibit 4.40: Forecast of Ancillary & Retailing Upsell Platforms (in USD Bn)
Exhibit 4.41: Forecast of Tour Operators & Package Travel Wholesalers (in USD Bn)
Exhibit 4.42: Forecast of Outbound Tour Operators (in USD Bn)
Exhibit 4.43: Forecast of Inbound & Destination Management Companies (in USD Bn)
Exhibit 4.44: Forecast of Dynamic Packaging Wholesalers (in USD Bn)
Exhibit 4.45: Forecast of Corporate Travel Management Companies (TMCs) (in USD Bn)
Exhibit 4.46: Forecast of Global TMC Networks (in USD Bn)
Exhibit 4.47: Forecast of Regional & Mid-Market TMCs (in USD Bn)
Exhibit 4.48: Forecast of Self-Booking Tool Integrators (in USD Bn)
Exhibit 6.49: Forecast of North America (in USD Bn)
Exhibit 6.50: Forecast of USA (in USD Bn)
Exhibit 6.51: Forecast of Canada (in USD Bn)
Exhibit 6.52: Forecast of Rest of North America (in USD Bn)
Exhibit 6.53: Forecast of Europe (in USD Bn)
Exhibit 6.54: Forecast of Germany (in USD Bn)
Exhibit 6.55: Forecast of the United Kingdom (in USD Bn)
Exhibit 6.56: Forecast of France (in USD Bn)
Exhibit 6.57: Forecast of Italy (in USD Bn)
Exhibit 6.58: Forecast of Spain (in USD Bn)
Exhibit 6.59: Forecast of Rest of Europe (in USD Bn)
Exhibit 6.60: Forecast of MEA (in USD Bn)
Exhibit 6.61: Forecast of Rest of MEA (in USD Bn)
Exhibit 6.62: Forecast of Asia Pacific (in USD Bn)
Exhibit 6.63: Forecast of China (in USD Bn)
Exhibit 6.64: Forecast of India (in USD Bn)
Exhibit 6.65: Forecast of Japan (in USD Bn)
Exhibit 6.66: Forecast of South Korea (in USD Bn)
Exhibit 6.67: Forecast of Australia (in USD Bn)
Exhibit 6.68: Forecast of Rest of Asia Pacific (in USD Bn)
Exhibit 6.69: Forecast of Latin America (in USD Bn)
Exhibit 6.70: Forecast of Brazil (in USD Bn)
Exhibit 6.71: Forecast of Mexico (in USD Bn)
Exhibit 6.72: Forecast of Colombia (in USD Bn)
Exhibit 6.73: Forecast of Rest of Latin America (in USD Bn)
Exhibit 6.74: Forecast of MEA Market YoY Growth Rate & CAGR Summary (in %)
Exhibit 6.75: Forecast of Saudi Arabia (in USD Bn)
Exhibit 6.76: Forecast of UAE (in USD Bn)
Exhibit 6.77: Forecast of South Africa (in USD Bn)
Frequently asked questions
What is the size of the B2B wholesale travel distribution market?
What is the CAGR of the B2B wholesale travel distribution market?
What is driving growth in the B2B wholesale travel distribution market?
Who are the leading companies in the B2B wholesale travel distribution market?
Which region dominates the B2B wholesale travel distribution market?
What segments are covered in this report?
What is the forecast period covered in this report?
Research Methodology
All MarketResearchReports.com strategic research reports follow a rigorous, multi-stage methodology combining AI-assisted data synthesis with expert analyst validation.
Systematic collection from 500+ verified sources including SEC filings, industry databases (Bloomberg, Statista, OECD), regulatory filings, trade publications, patent databases, and company annual reports. AI-assisted extraction identifies relevant data points across 10,000+ documents per report.
Dual-validation approach: bottom-up sizing aggregates segment-level production, consumption, and trade data; top-down sizing cross-validates against macroeconomic indicators and total addressable market estimates. Discrepancies >5% trigger analyst review.
Company profiles built from public financial disclosures, product launches, M&A activity, job postings (as capability proxies), and supply chain mapping. Market share estimates triangulated across revenue, capacity, and shipment data.
CAGR projections use time-series regression on 5-10 years of historical data, adjusted for identified demand drivers (technology adoption curves, regulatory catalysts, demographic shifts) and demand inhibitors (cost barriers, substitution risk). Scenario modeling covers base, optimistic, and conservative cases.
All quantitative outputs reviewed by a domain-specialist analyst before publication. Data triangulation requires minimum 3 independent sources for every key figure. Reports undergo a structured peer review against our 47-point quality checklist covering methodology, data citations, logical consistency, and formatting standards.
On-demand reports are generated at time of purchase, incorporating the most recent available data. Static reports are republished when underlying market conditions shift by >10% from baseline assumptions. Purchasers receive update notifications for 12 months.
Related reports
 Navadhi Market Research · Travel, Tourism & Hospitality
Global Next-Generation Dynamic Pricing Engines and Machine Learning in Airline Revenue Management Systems Market Strategic Research Report
The global market for next-generation dynamic pricing engines and machine learning in airline revenue management systems represents one of the most commercially cons…
Navadhi Market Research · Travel, Tourism & HospitalityGlobal eVTOL Urban Air Mobility and Tourism Shuttle Infrastructure Market Strategic Research Report
The global electric vertical takeoff and landing (eVTOL) urban air mobility and tourism shuttle infrastructure market is emerging as one of the most capital-intensiv…
Navadhi Market Research · Travel, Tourism & HospitalityGlobal Experiential and Fandom Tourism Infrastructure Market Strategic Research Report
The global experiential and fandom tourism infrastructure market sits at the intersection of entertainment IP, live event production, and destination development, en…
Need a customized version?
Get country-, segment- or company-specific intelligence tailored to your exact requirements.
Request custom research →Request a free sample
Receive a sample of Global B2B Wholesale Travel Distribution Market Strategic Research Report before you buy.
Customize This Report
Describe your specific requirements and our analysts will scope and deliver a tailored version.
Request Invoice
We will email a proforma invoice within 24 hours. Report access is granted upon payment confirmation.
Leading Brands in This Industry