

Global Digital Health & Remote Patient Monitoring Market Strategic Research Report

By Type: Continuous Glucose Monitors (CGM), Remote Cardiac Monitoring Devices, RPM Platforms and Clinical Software, Telehealth and Video Consultation, Sleep Disorder Monitoring (CPAP/BiPAP), Connected Vital Signs Monitors, Wearable Health Monitors (ECG/SpO2/BP), Hospital-at-Home and Post-Acute Monitoring, Mental Health and Behavioural RPM, Chronic Respiratory Monitoring, Other Digital Health and Diagnostics
By Application: Chronic Disease Management, Post-Acute and Hospital-at-Home, Elderly and Geriatric Care, Cardiology and Cardiac Care, Mental Health and Wellness, Oncology and Cancer Monitoring, Paediatric Care, Other Clinical Applications
Regional Forecast: Asia Pacific, Latin America, MEA, Europe, North America
Key Players: Abbott Laboratories, Dexcom Inc., ResMed Inc., Medtronic plc, iRhythm Technologies, Teladoc Health Inc., Philips N.V., Masimo Corporation, Insulet Corporation, Veeva Systems
Overview
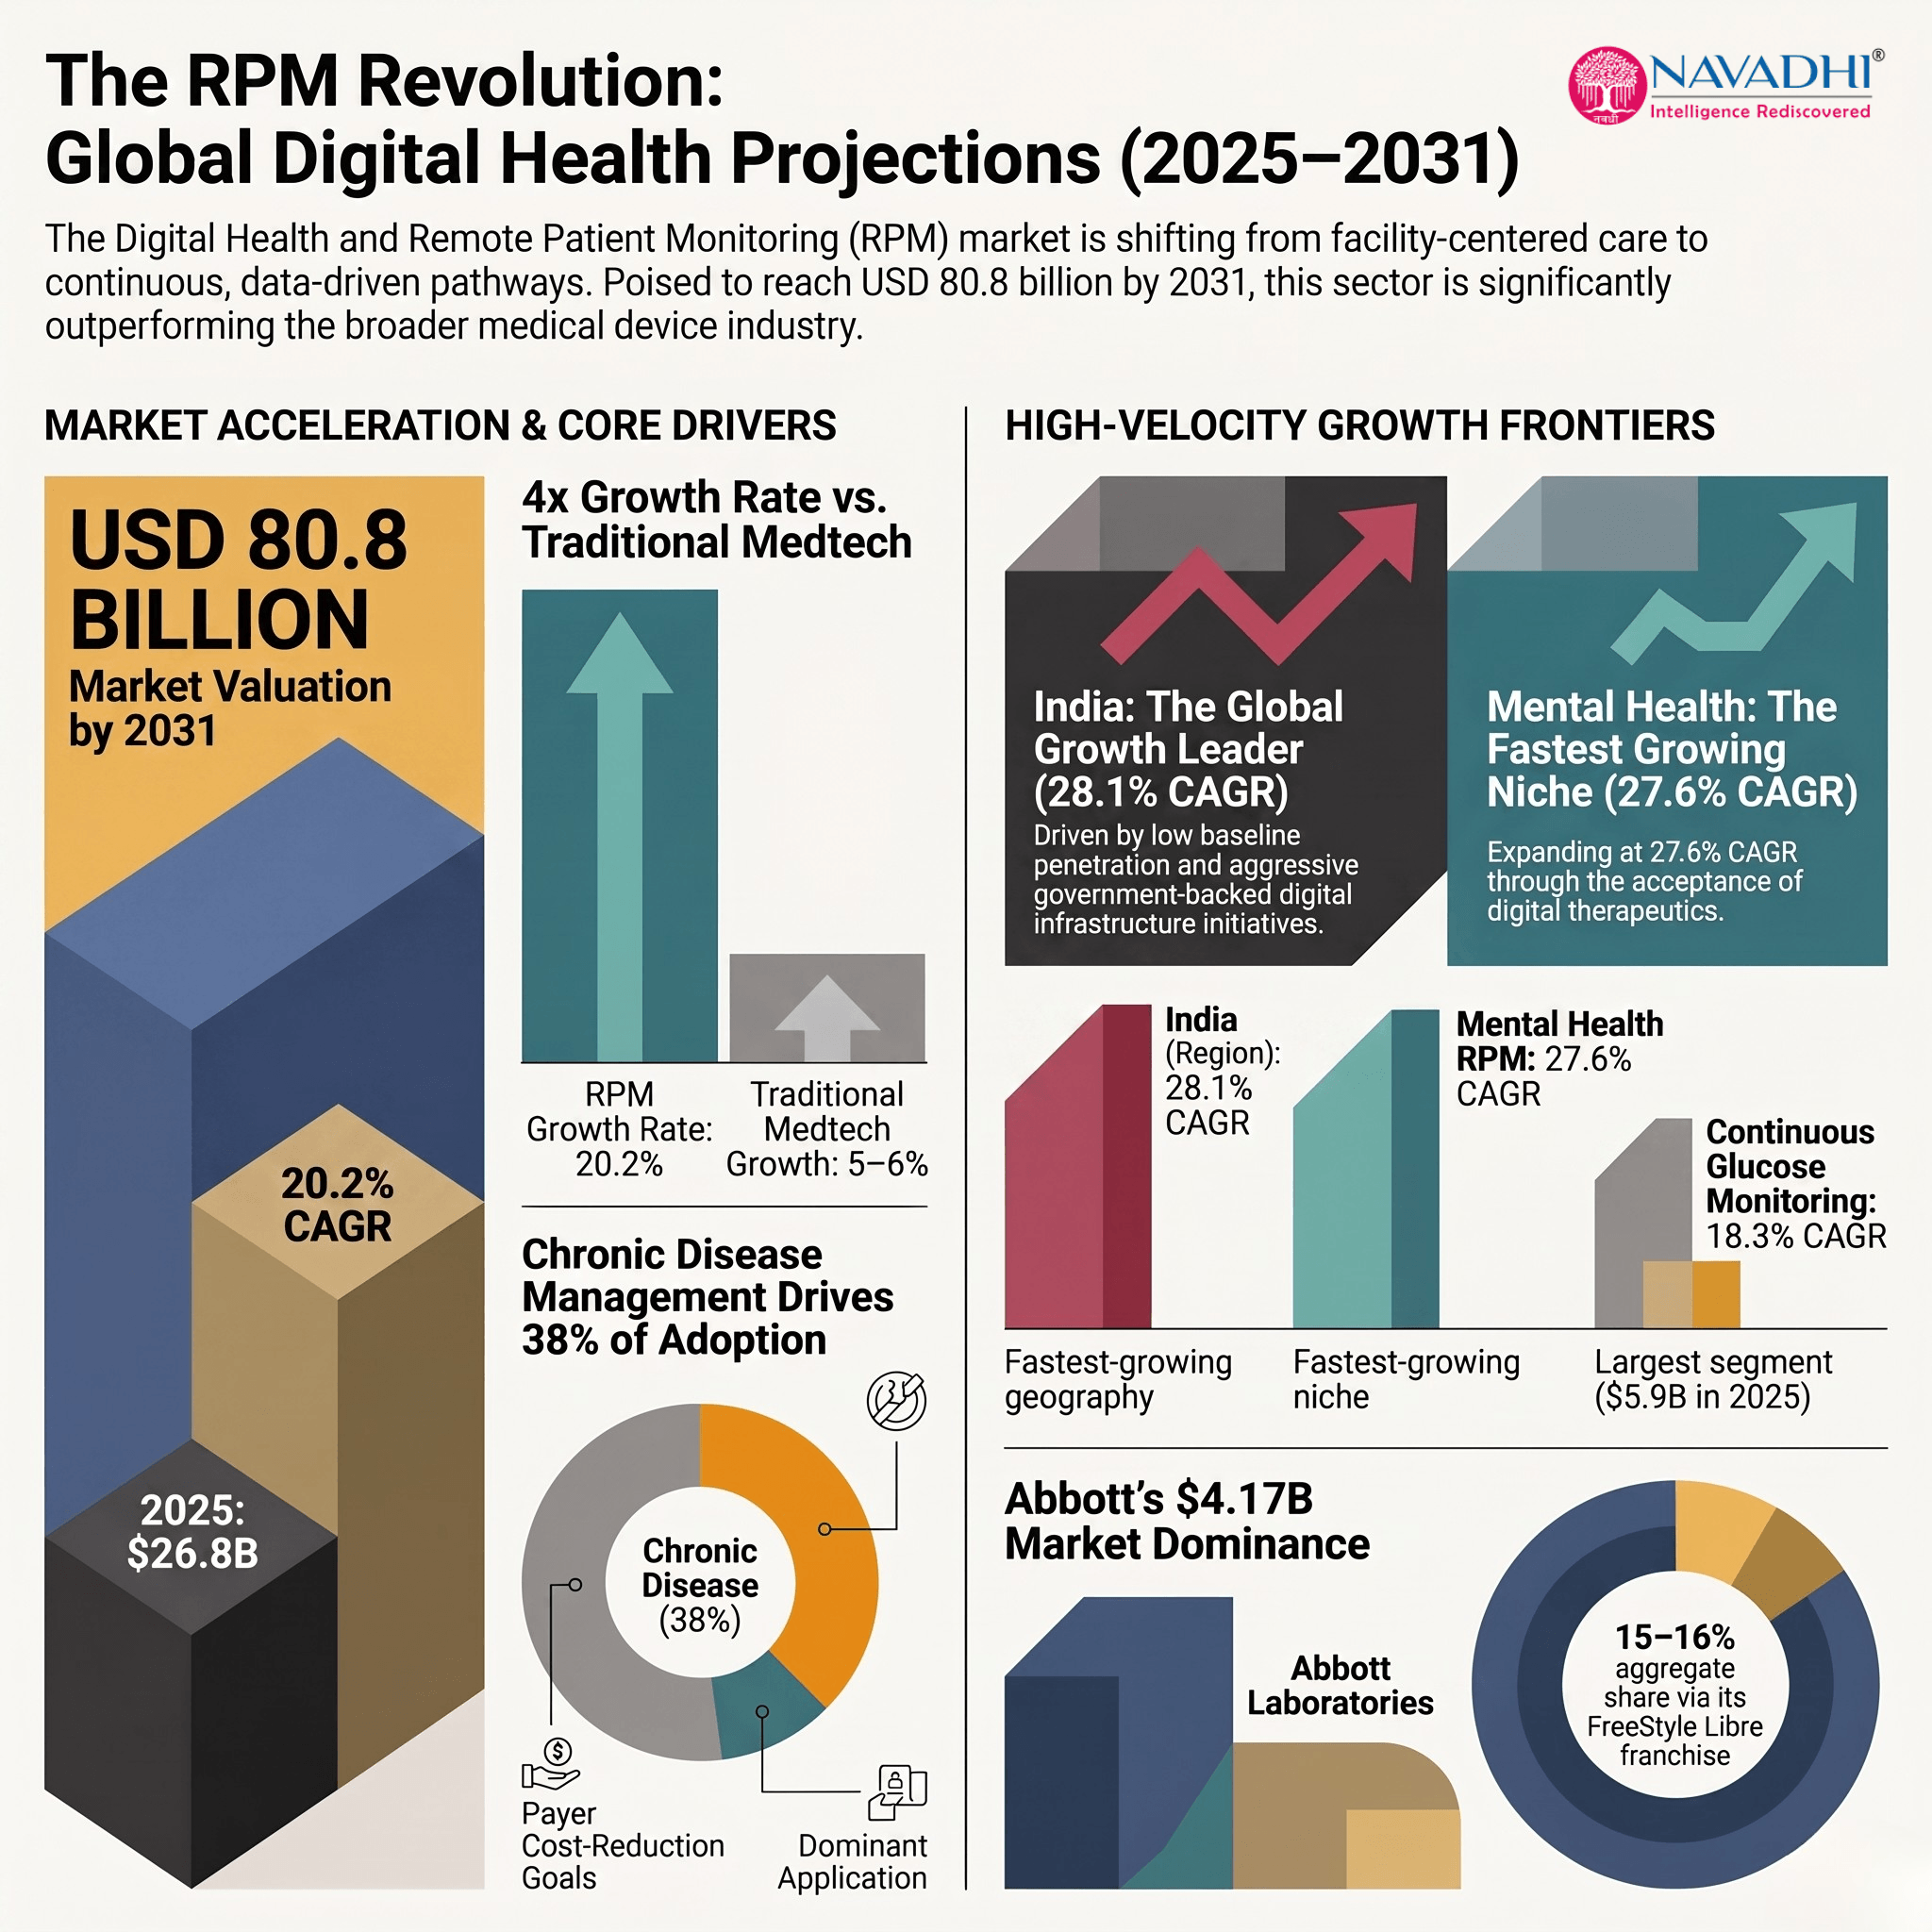
The Global Digital Health and Remote Patient Monitoring (RPM) market is undergoing a structural transformation, shifting healthcare-industry-strategic-research-report" title="Global Healthcare Industry Strategic Research Report">healthcare from episodic, facility-centered care to continuous, data-driven, patient-centric pathways. Driven by advanced biosensors, cloud infrastructure, AI diagnostics, and favorable reimbursement shifts, the market is poised to expand from USD 26.8 billion in 2025 to USD 80.8 billion by 2031. This represents a 20.2% CAGR, significantly outperforming the broader medical device sector’s 5–6% growth. For medtech leaders, payers, and providers, this category-defining expansion offers a critical mechanism to achieve structural efficiencies under value-based care models while addressing the demographic pressures of an aging global population.
Key Market Dimensions & Growth Catalysts
- Anchor Segment (Continuous Glucose Monitoring): CGM remains the largest market segment, accounting for 22.0% of the total market (USD 5.9 billion) in 2025. It is projected to nearly triple to USD 16.2 billion by 2031 (18.3% CAGR), remaining the primary engine of category volume.
- High-Growth Frontier (Mental Health RPM): Driven by the institutional acceptance of digital therapeutics and scalable, inter-session monitoring tools, Mental Health RPM represents the fastest-growing niche, expanding at a 27.6% CAGR through 2031.
- Dominant Application (Chronic Disease Management): Securing a 38.0% market share in 2025, chronic disease applications—spanning diabetes (CGM), sleep apnea (connected CPAP), and cardiology (arrhythmia monitoring)—remain the bedrock of commercial adoption due to their direct alignment with payer cost-reduction goals.
- Geographic Powerhouse (North America): Holding 42.0% of the global market in 2025, North America leads due to a mature regulatory and reimbursement landscape, specifically anchored by Medicare Part D, active CMS CPT billing codes (99453–99458), and the Hospital-at-Home Waiver Program.
- Emerging Market Acceleration (India): India represents the fastest-growing geographic opportunity with a 28.1% CAGR. Growth is catalyzed by low baseline penetration, expanding middle-class demand, and aggressive government-backed digital health infrastructure initiatives.
- Competitive Landscape Benchmark (Abbott Laboratories): Abbott commands a dominant 15–16% aggregate share of the global CGM and RPM market. This leadership is anchored by its FreeStyle Libre franchise, which delivered a market-leading USD 4.17 billion in FY2024 revenues.
Strategic Imperatives for Leadership
- Shift from Device-Centric to Ecosystem-Centric Models: Success in this rapidly scaling market requires shifting from selling standalone hardware to providing integrated, AI-driven data ecosystems that demonstrably improve clinical outcomes and reduce hospitalization costs.
- Target High-Velocity Micro-Markets: While North America and CGM offer immediate scale, players seeking breakout growth must establish early-mover advantages in high-velocity segments like Indian digital infrastructure and behavioral health RPM platforms.
Segment by type covered in the Global Digital Health and Remote Patient Monitoring (RPM) Report
- Continuous Glucose Monitors (CGM)
- Remote Cardiac Monitoring Devices
- RPM Platforms & Clinical Software
- Telehealth & Video Consultation
- Sleep Disorder Monitoring (CPAP/BiPAP)
- Connected Vital Signs Monitors
- Wearable Health Monitors (ECG/SpO2/BP)
- Hospital-at-Home & Post-Acute Monitoring
- Mental Health & Behavioural RPM
- Chronic Respiratory Monitoring
- Other Digital Health & Diagnostics
Segment by Application covered in the Global Digital Health and Remote Patient Monitoring (RPM) Report
- Chronic Disease Management
- Post-Acute & Hospital-at-Home
- Elderly & Geriatric Care
- Cardiology & Cardiac Care
- Mental Health & Wellness
- Oncology & Cancer Monitoring
- Paediatric Care
- Other Clinical Applications
Segment by Geography
North America
- USA
- Canada
Europe
- Germany
- UK
- France
- Netherlands
- Sweden
- Spain
- Rest of Europe
Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of APAC
Middle East and Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of MEA
Latin America
- Brazil
- Mexico
- Colombia
- Rest of LATAM
Market snapshot
Global Digital Health & Remote Patient Monitoring Market Strategic Research Report snapshot, 2025–2031
 © MarketResearchReports.comDisclaimer: The actual data may vary in the final report which undergoes verification check post order confirmation.
Segments covered in this report
Table of contents
01Executive Summary
- 1.1 Market Overview and Strategic Significance
- 1.2 Key Market Metrics at a Glance
- 1.3 Structural Growth Drivers: A Three-Pillar Framework
- 1.3.1 Pillar I — CGM Mass Market Penetration in Diabetes Management
- 1.3.2 Pillar II — Cloud-Connected Respiratory and Cardiac Monitoring Platform Expansion
- 1.3.3 Pillar III — Telehealth Infrastructure Normalisation and Chronic Disease Re-acceleration
- 1.4 Strategic Market Context and Competitive Landscape
- 1.4.1 From Fragmentation to Ecosystem Integration
- 1.4.2 Reimbursement Architecture as a Market Enabler
- 1.4.3 Regional Strategic Priorities
- 1.4.4 Competitive Concentration and Emerging Disruption Vectors
- 1.5 Report Scope and Analytical Boundaries
- 1.6 Report Navigation Guide
02Industry Overview & Forecast
- 2.1 Market Sizing and Historical Context
- 2.2 Forecast Overview: 2026–2031
- 2.3 Historical Actuals and Baseline Verification
- 2.4 Segmental Contribution to Growth
- 2.5 Application-Level Market Structure
- 2.6 Regional Dimension of the Forecast
- 2.7 Structural Integrity of the Forecast: Key Analytical Considerations
03Market Segmentation by Type
- 3.1 Overview
- 3.2 Continuous Glucose Monitors (CGM)
- 3.3 Remote Cardiac Monitoring Devices
- 3.4 RPM Platforms and Clinical Software
- 3.5 Telehealth and Video Consultation Platforms
- 3.6 Sleep Disorder Monitoring (CPAP/BiPAP Connected Platforms)
- 3.7 Connected Vital Signs Monitors
- 3.8 Wearable Health Monitors (ECG/SpO₂/Blood Pressure)
- 3.9 Hospital-at-Home and Post-Acute Monitoring
- 3.10 Mental Health and Behavioural RPM
- 3.11 Chronic Respiratory Monitoring
- 3.12 Other Digital Health and Diagnostics
- 3.13 Cross-Segment Share Analysis and Structural Observations
04Market Segmentation by Application
- 4.1 Overview
- 4.2 Chronic Disease Management
- 4.3 Post-Acute Care & Hospital-at-Home
- 4.4 Elderly & Geriatric Care
- 4.5 Cardiology & Cardiac Care
- 4.6 Mental Health & Wellness
- 4.7 Oncology & Cancer Monitoring
- 4.8 Paediatric Care
- 4.9 Other Clinical Applications
- 4.10 Application Segment Synthesis: Share Shift Analysis
05Regional Market Forecast
- 5.1 North America
- 5.1.1 Regional Overview
- 5.1.2 Key Growth Drivers
- 5.1.3 Regulatory & Infrastructure Landscape
- 5.1.4 Country-Level Analysis
- 5.1.5 Market Forecast 2025–2031
- 5.2 Europe
- 5.2.1 Regional Overview
- 5.2.2 Key Growth Drivers
- 5.2.3 Regulatory & Infrastructure Landscape
- 5.2.4 Country-Level Analysis
- 5.2.5 Market Forecast 2025–2031
- 5.3 Asia-Pacific
- 5.3.1 Regional Overview
- 5.3.2 Key Growth Drivers
- 5.3.3 Regulatory & Infrastructure Landscape
- 5.3.4 Country-Level Analysis
- 5.3.5 Market Forecast 2025–2031
- 5.4 Middle East & Africa
- 5.4.1 Regional Overview
- 5.4.2 Key Growth Drivers
- 5.4.3 Regulatory & Infrastructure Landscape
- 5.4.4 Country-Level Analysis
- 5.4.5 Market Forecast 2025–2031
- 5.5 Latin America
- 5.5.1 Regional Overview
- 5.5.2 Key Growth Drivers
- 5.5.3 Regulatory & Infrastructure Landscape
- 5.5.4 Country-Level Analysis
- 5.5.5 Market Forecast 2025–2031
06Country-Level Market Forecast
- 6.1 North America
- 6.1.1 USA
- 6.1.2 Canada
- 6.2 Europe
- 6.2.1 Germany
- 6.2.2 UK
- 6.2.3 France
- 6.2.4 Netherlands
- 6.2.5 Sweden
- 6.2.6 Spain
- 6.2.7 Rest of Europe
- 6.3 Asia-Pacific
- 6.3.1 China
- 6.3.2 Japan
- 6.3.3 India
- 6.3.4 Australia
- 6.3.5 South Korea
- 6.3.6 Rest of APAC
- 6.4 Middle East & Africa
- 6.4.1 Saudi Arabia
- 6.4.2 UAE
- 6.4.3 Israel
- 6.4.4 South Africa
- 6.4.5 Rest of MEA
- 6.5 Latin America
- 6.5.1 Brazil
- 6.5.2 Mexico
- 6.5.3 Colombia
- 6.5.4 Rest of LATAM
07Growth Drivers & Inhibitors
- 7.1 Structural Growth Drivers
- 7.1.1 Driver 1: Continuous Glucose Monitoring Penetration Deficit in Type 2 Diabetes — A Decade-Long Structural Growth Runway
- 7.1.2 Driver 2: Reimbursement Framework Expansion — CMS Remote Patient Monitoring Codes and International Coverage Architectures
- 7.1.3 Driver 3: Artificial Intelligence-Augmented Predictive Monitoring — Transition from Passive Data Collection to Clinical Decision Support
- 7.1.4 Driver 4: Hospital-at-Home Policy Institutionalisation and High-Acuity Remote Care Economics
- 7.1.5 Driver 5: Ageing Demographics and Chronic Disease Comorbidity Burden — Non-Discretionary RPM Demand
- 7.2 Market Inhibitors and Structural Constraints
- 7.2.1 Inhibitor 1: Health Data Privacy Regulation — GDPR, HIPAA, and Emerging National Frameworks
- 7.2.2 Inhibitor 2: Reimbursement Rate Uncertainty and Payer Access Barriers
- 7.2.3 Inhibitor 3: Patient Engagement Deficits, Digital Health Literacy, and the Adherence Gap
- 7.2.4 Inhibitor 4: Regulatory Pathway Complexity for Medical-Grade Digital Health Devices and AI Diagnostics
- 7.2.5 Inhibitor 5: Technical Infrastructure Limitations — Sensor Accuracy, EHR Interoperability, and Clinical Alarm Fatigue
- 7.2.6 Summary Assessment: Driver-Inhibitor Balance
08Key Company Profiles
- 8.1 Abbott Laboratories
- 8.1.1 Company Overview
- 8.1.2 Key Products & Segments
- 8.1.3 Financial Performance (2023–2025)
- 8.1.4 Business Strategy
- 8.1.5 SWOT Analysis
- 8.1.6 Strategic Implications (2025–2031)
- 8.2 Dexcom Inc.
- 8.2.1 Company Overview
- 8.2.2 Key Products & Segments
- 8.2.3 Financial Performance (2023–2025)
- 8.2.4 Business Strategy
- 8.2.5 SWOT Analysis
- 8.2.6 Strategic Implications (2025–2031)
- 8.3 ResMed Inc.
- 8.3.1 Company Overview
- 8.3.2 Key Products & Segments
- 8.3.3 Financial Performance (2023–2025)
- 8.3.4 Business Strategy
- 8.3.5 SWOT Analysis
- 8.3.6 Strategic Implications (2025–2031)
- 8.4 Medtronic plc
- 8.4.1 Company Overview
- 8.4.2 Key Products & Segments
- 8.4.3 Financial Performance (2023–2025)
- 8.4.4 Business Strategy
- 8.4.5 SWOT Analysis
- 8.4.6 Strategic Implications (2025–2031)
- 8.5 iRhythm Technologies
- 8.5.1 Company Overview
- 8.5.2 Key Products & Segments
- 8.5.3 Financial Performance (2023–2025)
- 8.5.4 Business Strategy
- 8.5.5 SWOT Analysis
- 8.5.6 Strategic Implications (2025–2031)
- 8.6 Teladoc Health Inc.
- 8.6.1 Company Overview
- 8.6.2 Key Products & Segments
- 8.6.3 Financial Performance (2023–2025)
- 8.6.4 Business Strategy
- 8.6.5 SWOT Analysis
- 8.6.6 Strategic Implications (2025–2031)
- 8.7 Philips N.V.
- 8.7.1 Company Overview
- 8.7.2 Key Products & Segments
- 8.7.3 Financial Performance (2023–2025)
- 8.7.4 Business Strategy
- 8.7.5 SWOT Analysis
- 8.7.6 Strategic Implications (2025–2031)
- 8.8 Masimo Corporation
- 8.8.1 Company Overview
- 8.8.2 Key Products & Segments
- 8.8.3 Financial Performance (2023–2025)
- 8.8.4 Business Strategy
- 8.8.5 SWOT Analysis
- 8.8.6 Strategic Implications (2025–2031)
- 8.9 Insulet Corporation
- 8.9.1 Company Overview
- 8.9.2 Key Products & Segments
- 8.9.3 Financial Performance (2023–2025)
- 8.9.4 Business Strategy
- 8.9.5 SWOT Analysis
- 8.9.6 Strategic Implications (2025–2031)
- 8.10 Veeva Systems
- 8.10.1 Company Overview
- 8.10.2 Key Products & Segments
- 8.10.3 Financial Performance (2023–2025)
- 8.10.4 Business Strategy
- 8.10.5 SWOT Analysis
- 8.10.6 Strategic Implications (2025–2031)
09Competitive Landscape
- 9.1 Competitive Landscape Overview
- 9.2 Competitive Intensity Assessment
- 9.2.1 Tier Classification and Revenue Benchmarking
- 9.2.2 Tier 1: Scale Incumbents and Structural Dominance
- 9.2.3 Tier 2: Pure-Play Specialists and Margin Leadership
- 9.2.4 Tier 3: Niche Challengers and Disruption Vectors
- 9.2.5 Pricing Environment and Barriers to Entry and Exit
- 9.3 Key Player Strategies & Positioning
- 9.3.1 Strategic Group Map Narrative
- 9.3.2 Differentiation Strategies
- 9.3.3 Geographic Strongholds
- 9.3.4 Selected M&A and Partnership Activity (2022–Present)
- 9.3.5 R&D and Technology Investment Trends
- 9.4 Competitive Dynamics & Strategic Outlook
- 9.4.1 Emerging Competitive Threats
- 9.4.2 Consolidation vs. Fragmentation Outlook
- 9.4.3 Competitive Response Matrix
- 9.4.4 Strategic Recommendations for 2025–2031
10Porter's Five Forces Analysis
- 10.1 Threat of New Entrants
- 10.2 Bargaining Power of Buyers
- 10.3 Bargaining Power of Suppliers
- 10.4 Threat of Substitutes
- 10.5 Competitive Rivalry
11PESTLE Analysis
- 11.1 Strategic Environmental Assessment of the Global Digital Health & Remote Patient Monitoring Market
- 11.2 Political Factors
- 11.2.1 US Centers for Medicare & Medicaid Services (CMS) Reimbursement Policy
- 11.2.2 UK National Health Service Digital Transformation
- 11.2.3 India National Digital Health Mission and eSanjeevani
- 11.2.4 Cross-Jurisdictional Political Risk Assessment
- 11.3 Economic Factors
- 11.3.1 Healthcare Cost Avoidance as the Primary Economic Proposition
- 11.3.2 Employer Health Benefit Economics
- 11.3.3 Patient Co-Pay Affordability and Premium Device Access
- 11.3.4 Macroeconomic Sensitivity Matrix
- 11.4 Social Factors
- 11.4.1 Post-COVID Behavioural Normalisation of Remote Healthcare
- 11.4.2 Mental Health Destigmatisation and Demand Expansion
- 11.4.3 Ageing Population and Home-Based Care Preference
- 11.4.4 Health Literacy and Patient Empowerment
- 11.4.5 Digital Divide: Social Equity Risk
- 11.5 Technological Factors
- 11.5.1 Artificial Intelligence and Machine Learning Integration
- 11.5.2 Edge Computing and On-Device AI Inference
- 11.5.3 5G Connectivity and Real-Time High-Frequency Biometric Transmission
- 11.5.4 Non-Invasive Glucose Monitoring: The Most Consequential Emerging Technology
- 11.5.5 Federated Learning and Privacy-Preserving AI Infrastructure
- 11.6 Legal and Regulatory Factors
- 11.6.1 US FDA Digital Health Center of Excellence and SaMD Guidance
- 11.6.2 EU Medical Device Regulation (MDR) Compliance Complexity
- 11.6.3 Germany DiGA Framework: A Reimbursement Innovation Model
- 11.6.4 HIPAA, GDPR, and Emerging Data Sovereignty Frameworks
- 11.6.5 CMS RPM Documentation Requirements as a Commercial Constraint
- 11.7 Environmental Factors
- 11.7.1 Medical Plastics and Single-Use Device Waste
- 11.7.2 Hospital-at-Home and Net Environmental Benefits
- 11.7.3 Cloud Computing Carbon Footprint
- 11.7.4 Sustainability as a Competitive Differentiator
- 11.8 PESTLE Synthesis: Integrated Strategic Implications
12SWOT Analysis
- 12.1 Strategic Assessment of the Global Digital Health & Remote Patient Monitoring Market (2026–2031)
- 12.2 Strengths
- 12.2.1 Proven Revenue Scale and Accelerating Commercial Momentum
- 12.2.2 Structural Tailwinds from Chronic Disease Epidemiology
- 12.2.3 Robust and Expanding Reimbursement Infrastructure
- 12.2.4 Technology Platform Maturity and Clinical Integration
- 12.2.5 Favourable Demographic Dynamics Across Multiple Geographies
- 12.3 Weaknesses
- 12.3.1 Heavy Revenue Concentration in a Small Number of Product Categories and Geographies
- 12.3.2 Persistent Diagnostic and Clinical Validation Gaps
- 12.3.3 Post-COVID Revenue Normalisation in Telehealth Platforms
- 12.3.4 Interoperability Fragmentation and Data Standardisation Challenges
- 12.3.5 Unequal Access and Digital Health Literacy Barriers
- 12.4 Opportunities
- 12.4.1 Undiagnosed and Undertreated Patient Populations Represent Massive Untapped Addressable Markets
- 12.4.2 Asia-Pacific Emerging as the Primary Long-Term Growth Engine
- 12.4.3 Hospital-at-Home as a Systemic Healthcare Delivery Transformation
- 12.4.4 RPM Platforms and Clinical Software: The Highest-Multiple Growth Category
- 12.4.5 Mental Health and Behavioural RPM: Early-Stage Market with Structural Tailwinds
- 12.4.6 Artificial Intelligence and Predictive Analytics Integration
- 12.5 Threats
- 12.5.1 Reimbursement Policy Vulnerability and CMS Rate Compression Risk
- 12.5.2 Cybersecurity and Patient Data Privacy as Systemic Risk Factors
- 12.5.3 Big Technology Platform Entry and Competitive Disruption
- 12.5.4 Regulatory Complexity and Diverging International Standards
- 12.5.5 Patient Engagement, Adherence, and Digital Fatigue Risks
- 12.5.6 Competitive Commoditisation of Core Monitoring Hardware
- 12.6 SWOT Summary Matrix
13Future Trends & Strategic Outlook
- 13.1 Executive Summary of Forward-Looking Dynamics
- 13.2 Trend Vector 1: Artificial Intelligence Integration Across the Clinical Monitoring Continuum
- 13.2.1 Current State Assessment
- 13.2.2 Quantified Growth Opportunity
- 13.2.3 Key Developments to Monitor (2026–2028)
- 13.3 Trend Vector 2: Reimbursement Framework Expansion and Its Revenue Multiplier Effect
- 13.3.1 The CMS RPM Codes as a Revenue Catalyst
- 13.3.2 CGM Medicare Part D: A Paradigm-Setting Policy Precedent
- 13.3.3 International Reimbursement Trajectory
- 13.4 Trend Vector 3: The Hospital-at-Home Revolution and Its Market Infrastructure Requirements
- 13.4.1 CMS Waiver Programme as Market Foundation
- 13.4.2 Enabling Technology Requirements and Commercial Implications
- 13.4.3 Reimbursement Risk and Programme Extension Dependency
- 13.5 Trend Vector 4: Mental Health & Behavioural Monitoring as the Next High-Growth Frontier
- 13.5.1 Market Sizing and Growth Trajectory
- 13.5.2 Demand Drivers: Epidemiological and Employer-Mandate Tailwinds
- 13.5.3 Technological Evolution: Passive Monitoring and Precision Psychiatry
- 13.6 Trend Vector 5: Asia-Pacific as the Strategic Growth Fulcrum (2027–2031)
- 13.6.1 Regional Growth Trajectory
- 13.6.2 Country-Level Growth Drivers
- 13.6.3 Regulatory and Infrastructure Considerations
- 13.7 Trend Vector 6: Value-Based Care Contracting and the Shift from Fee-for-Service to Outcomes-Based Revenue Models
- 13.7.1 Structural Commercial Model Transformation
- 13.7.2 CMS Innovation Center Models as Commercial Proof Points
- 13.7.3 Implications for Market Structure and M&A Activity
- 13.8 Trend Vector 7: Wearable Technology Convergence and Consumer-to-Clinical Grade Pathway
- 13.8.1 The Regulatory Clearance Accelerator
- 13.8.2 Market Sizing and Segment Evolution
- 13.8.3 Competitive Dynamics: Consumer Giants vs. Medical Device Specialists
- 13.9 Synthesis: Integrated Outlook Matrix for 2026–2031
- 13.9.1 Forecast Confidence Assessment
- 13.9.2 Highest-Conviction Growth Segments for 2026–2031
- 13.9.3 Strategic Imperatives for Market Participants
Tables and figures
List of Exhibits
Exhibit 2.1: Forecast of Global Market YoY Growth Rate & CAGR Summary (in %)
Exhibit 2.2: Forecast of Global (in USD Bn)
Exhibit 2.3: Forecast of North America (in USD Bn)
Exhibit 2.4: Forecast of Europe (in USD Bn)
Exhibit 2.5: Forecast of Asia-Pacific (in USD Bn)
Exhibit 2.6: Forecast of Middle East & Africa (in USD Bn)
Exhibit 2.7: Forecast of Latin America (in USD Bn)
Exhibit 3.8: Forecast of Continuous Glucose Monitors (CGM) (in USD Bn)
Exhibit 3.9: Forecast of Remote Cardiac Monitoring Devices (in USD Bn)
Exhibit 3.10: Forecast of RPM Platforms & Clinical Software (in USD Bn)
Exhibit 3.11: Forecast of Telehealth & Video Consultation (in USD Bn)
Exhibit 3.12: Forecast of Sleep Disorder Monitoring (CPAP/BiPAP) (in USD Bn)
Exhibit 3.13: Forecast of Connected Vital Signs Monitors (in USD Bn)
Exhibit 3.14: Forecast of Wearable Health Monitors (ECG/SpO2/BP) (in USD Bn)
Exhibit 3.15: Forecast of Hospital-at-Home & Post-Acute Monitoring (in USD Bn)
Exhibit 3.16: Forecast of Mental Health & Behavioural RPM (in USD Bn)
Exhibit 3.17: Forecast of Chronic Respiratory Monitoring (in USD Bn)
Exhibit 3.18: Forecast of Other Digital Health & Diagnostics (in USD Bn)
Exhibit 4.19: Forecast of Chronic Disease Management (in USD Bn)
Exhibit 4.20: Forecast of Post-Acute & Hospital-at-Home (in USD Bn)
Exhibit 4.21: Forecast of Elderly & Geriatric Care (in USD Bn)
Exhibit 4.22: Forecast of Cardiology & Cardiac Care (in USD Bn)
Exhibit 4.23: Forecast of Mental Health & Wellness (in USD Bn)
Exhibit 4.24: Forecast of Oncology & Cancer Monitoring (in USD Bn)
Exhibit 4.25: Forecast of Paediatric Care (in USD Bn)
Exhibit 4.26: Forecast of Other Clinical Applications (in USD Bn)
Exhibit 6.27: Forecast of North America (in USD Bn)
Exhibit 6.28: Forecast of USA (in USD Bn)
Exhibit 6.29: Forecast of Canada (in USD Bn)
Exhibit 6.30: Forecast of Europe (in USD Bn)
Exhibit 6.31: Forecast of Germany (in USD Bn)
Exhibit 6.32: Forecast of UK (in USD Bn)
Exhibit 6.33: Forecast of France (in USD Bn)
Exhibit 6.34: Forecast of Netherlands (in USD Bn)
Exhibit 6.35: Forecast of Sweden (in USD Bn)
Exhibit 6.36: Forecast of Spain (in USD Bn)
Exhibit 6.37: Forecast of Rest of Europe (in USD Bn)
Exhibit 6.38: Forecast of Asia-Pacific (in USD Bn)
Exhibit 6.39: Forecast of China (in USD Bn)
Exhibit 6.40: Forecast of Japan (in USD Bn)
Exhibit 6.41: Forecast of India (in USD Bn)
Exhibit 6.42: Forecast of Australia (in USD Bn)
Exhibit 6.43: Forecast of South Korea (in USD Bn)
Exhibit 6.44: Forecast of Rest of APAC (in USD Bn)
Exhibit 6.45: Forecast of Middle East & Africa (in USD Bn)
Exhibit 6.46: Forecast of Saudi Arabia (in USD Bn)
Exhibit 6.47: Forecast of UAE (in USD Bn)
Exhibit 6.48: Forecast of Israel (in USD Bn)
Exhibit 6.49: Forecast of South Africa (in USD Bn)
Exhibit 6.50: Forecast of Rest of MEA (in USD Bn)
Exhibit 6.51: Forecast of Latin America (in USD Bn)
Exhibit 6.52: Forecast of Brazil (in USD Bn)
Exhibit 6.53: Forecast of Mexico (in USD Bn)
Exhibit 6.54: Forecast of Colombia (in USD Bn)
Exhibit 6.55: Forecast of Rest of LATAM (in USD Bn)
Frequently asked questions
What is the size of the remote patient monitoring systems market?
What is the CAGR of the remote patient monitoring systems market?
What is driving growth in the remote patient monitoring systems market?
Who are the leading companies in the remote patient monitoring systems market?
Which region dominates the remote patient monitoring systems market?
What segments are covered in this report?
What is the forecast period covered in this report?
Research Methodology
All MarketResearchReports.com strategic research reports follow a rigorous, multi-stage methodology combining AI-assisted data synthesis with expert analyst validation.
Systematic collection from 500+ verified sources including SEC filings, industry databases (Bloomberg, Statista, OECD), regulatory filings, trade publications, patent databases, and company annual reports. AI-assisted extraction identifies relevant data points across 10,000+ documents per report.
Dual-validation approach: bottom-up sizing aggregates segment-level production, consumption, and trade data; top-down sizing cross-validates against macroeconomic indicators and total addressable market estimates. Discrepancies >5% trigger analyst review.
Company profiles built from public financial disclosures, product launches, M&A activity, job postings (as capability proxies), and supply chain mapping. Market share estimates triangulated across revenue, capacity, and shipment data.
CAGR projections use time-series regression on 5-10 years of historical data, adjusted for identified demand drivers (technology adoption curves, regulatory catalysts, demographic shifts) and demand inhibitors (cost barriers, substitution risk). Scenario modeling covers base, optimistic, and conservative cases.
All quantitative outputs reviewed by a domain-specialist analyst before publication. Data triangulation requires minimum 3 independent sources for every key figure. Reports undergo a structured peer review against our 47-point quality checklist covering methodology, data citations, logical consistency, and formatting standards.
On-demand reports are generated at time of purchase, incorporating the most recent available data. Static reports are republished when underlying market conditions shift by >10% from baseline assumptions. Purchasers receive update notifications for 12 months.
Related reports
 Navadhi Market Research · Healthcare & Medical Devices
Global Wireless Infusion Pump Safety Market Strategic Research Report
The global wireless infusion pump safety market occupies a critical intersection of medical device technology, patient safety infrastructure, and hospital informatio…
Navadhi Market Research · Healthcare & Medical DevicesGlobal Smart Medical Waste Segregation Market Strategic Research Report
The global smart medical waste segregation market occupies a critical intersection of healthcare-industry-strategic-research-report" title="Global Healthcare Industr…
Navadhi Market Research · Healthcare & Medical DevicesGlobal Microfluidic Point of Care Diagnostics Market Strategic Research Report
The global microfluidic point of care (POC) diagnostics market represents one of the most commercially consequential intersections of materials science, biomedical e…
Need a customized version?
Get country-, segment- or company-specific intelligence tailored to your exact requirements.
Request custom research →Request a free sample
Receive a sample of Global Digital Health & Remote Patient Monitoring Market Strategic Research Report before you buy.
Customize This Report
Describe your specific requirements and our analysts will scope and deliver a tailored version.
Request Invoice
We will email a proforma invoice within 24 hours. Report access is granted upon payment confirmation.
Leading Brands in This Industry





